Private Credit AI Platforms — Competitor Deep-Dive
Researched 4 July 2026 · Independent research on nine AI platforms in private credit / private markets · Demo videos stream via YouTube/Loom; sources linked inline.
Five key findings
- BlueFlame was acquired by Datasite (July 2025). The "vendor-owned workspace" worry is now literal fact — it is the AI layer of a data-room vendor.
- Chronograph raised $140M+ from Sixth Street and launched a dedicated private credit platform (June 2026) — covenant monitoring across tranches, EBITDA add-back validation. Moving into monitoring territory with heavy capital. Still post-investment only.
- F2 is the most complete credit-first platform of the nine. Excel-native "OS for private markets": screening → underwriting → IC memo → monitoring. ~$120K ACV, Live Oak Bank & Decathlon named. Its monitoring/fund-reporting is still immature.
- Quantpillar is not a real vendor. 2-person borrower-side AI-CFO startup; the lender "Portfolio Health Monitor" on its site is a static HTML mockup, not a product. Drop it; recheck in 6–12 months.
- 7 of 9 companies have zero authentic reviews. Only Hebbia (G2 4.3/5) and Rogo (harsh WSO threads) have real user evidence. Wall Street Oasis beats G2 as a source here. The market has not locked in users yet.
Market map — four clusters
| Cluster | Companies | What they actually sell | What they don't have |
|---|---|---|---|
| 1 · Monitoring & LP reporting | Chronograph | Quarterly data collection, valuations, push-button LP reports; $5.9T monitored | Underwriting, decisioning, origination |
| 2 · ABF operating systems | Cardo AI | Post-close ops for structured credit: loan tapes, borrowing bases, waterfalls, surveillance | Credit decisions; bespoke single-name lending |
| 3 · AI deal workspaces | BlueFlame (Datasite), Hebbia, Rogo, Auquan | Chat/agents that read documents and draft memos, decks, reports | System of record, loan-level data model, decision engine |
| 4 · Diligence automation | Keye, F2 (outgrown it), Hebbia (partly) | Data room in → analyses out; deterministic math (Keye/F2) | Keye: anything credit. F2: mature monitoring/LP reporting |
Notably: no vendor yet covers bespoke lower-mid-market credit end-to-end — underwriting, decisioning, monitoring, and LP reporting on one evidence layer remains open whitespace.
Head-to-head numbers
| Founded | Funding | People | Scale claim | Pricing signal | Real reviews | Credit-native? | |
|---|---|---|---|---|---|---|---|
| Cardo AI | 2018 | $15M A (Blackstone co-led) | ~125 | $100bn+ assets on platform | Six-figure ACV (inferred) | None | Yes — post-close ABF ops |
| BlueFlame | 2023 | $5M → acquired (Datasite '25) | ~40 at exit | 120+ firms, ~3,000 users | Custom enterprise | G2: 0 reviews | Partly — 1 solution page |
| Chronograph | 2016 | $160M+ (Sixth Street $140M '26) | ~175 | $5.9T monitored, 15k funds | ~$50–500K+/yr (3rd-party est.) | None | New credit platform 6/26 |
| Quantpillar | 2024 | None found | 2 | None verifiable | $24–48K/yr (self-pub) | None | No — marketing only |
| Auquan | 2018* | ~$20M (quiet A, £34M post) | ~50 | "40% of top-50 FIs"; 2,700 credits at one bank | ~$500–1,000/document | Marginal | Yes — Credit Agent 9/25 |
| Keye | 2024 (YC F24) | $5M seed (Sorenson+GC) | ~3–15 | "$1.4T+ AUM of users" | Unknown ($30–80K unreliable) | None independent | No — PE equity only |
| F2 | 2025 (Arc spinout) | $24M (HighlandX, NFX, YC, BCV) | ~15 | 100+ funds/banks, $400B+ AUM clients | ~$120K ACV, ~25 seats | None (10 months old) | Yes — core market |
| Hebbia | 2020 | $161M ($130M B, a16z, ~$700M val) | ~150 | 1B pages; ~40% top asset mgrs; $13M ARR mid-'24 | ~$10K/seat/yr | G2 4.3/5 (11) | Strong use case (OHA), not credit-native |
| Rogo | 2021 | $300M+ ($2B val, Kleiner D) | ~150 | 35k users, 250–300 institutions; ~$15M rev '25 | ~$3.3K/seat/yr (est.) | Trustpilot 2 (neg); WSO harsh | Minimal — sell-side first |
*Auquan founded 2016–18 as a quant platform; pivoted to agents late 2023. All numbers sourced in briefs/.
Cardo AI ABF operating system
Post-close ABF operations leadercardoai.com · NY + Milan/London/Tirana
What it actually is
Software that runs asset-based finance structures after the deal closes: loan tapes in, eligibility tests, borrowing bases, payment waterfalls, covenant surveillance, investor reports out. Customers: Blackstone (also investor), Fasanara, Encina Lender Finance, Multitude Bank, doValue. Built for structures with many repeatable assets — not bespoke single-name loans.
Who uses it daily & what they do
- Investment-operations and surveillance staff (Blackstone's testimonial is from an SMD of Investment Operations — not an underwriter)
- Upload loan tape → "Loan Data Agent" standardizes it (claim: 4 hrs → 80 s)
- Upload credit agreement PDF → Document Reader extracts covenants, triggers, eligibility, cure periods
- Run eligibility/concentration tests; compute borrowing base; process drawdowns (<5 s claim)
- Drag-and-drop waterfall designer → simulate → execute real payment runs ("penny perfect")
- Borrower financials arrive → covenant engine flags breaches automatically
- Cash-flow models & stress tests on live Bloomberg curves; investor/insurance/regulatory reports from templates
Demos
Leadership roundtable, Jun 2026 (42 min) — product, agents, and data strategy. Talking heads; no public screen demo exists.
Founder podcast: "Modernizing Structured-Credit Infrastructure" (Oct 2024).
Product screenshots live in their changelog (site blocks scrapers — open in browser): waterfall builder · Document Reader · covenant monitoring
Bottom line
Best reference for data standardization, facility/borrowing-base logic, waterfall math, surveillance, investor reporting. No credit decisioning at all — their agents automate ops, not judgment. Its strength is post-close operations; everything pre-close (origination, underwriting, decisioning) is out of scope.
BlueFlame AI AI deal workspace
Now a Datasite featureblueflame.ai · NYC · acquired by Datasite July 2025
What it actually is
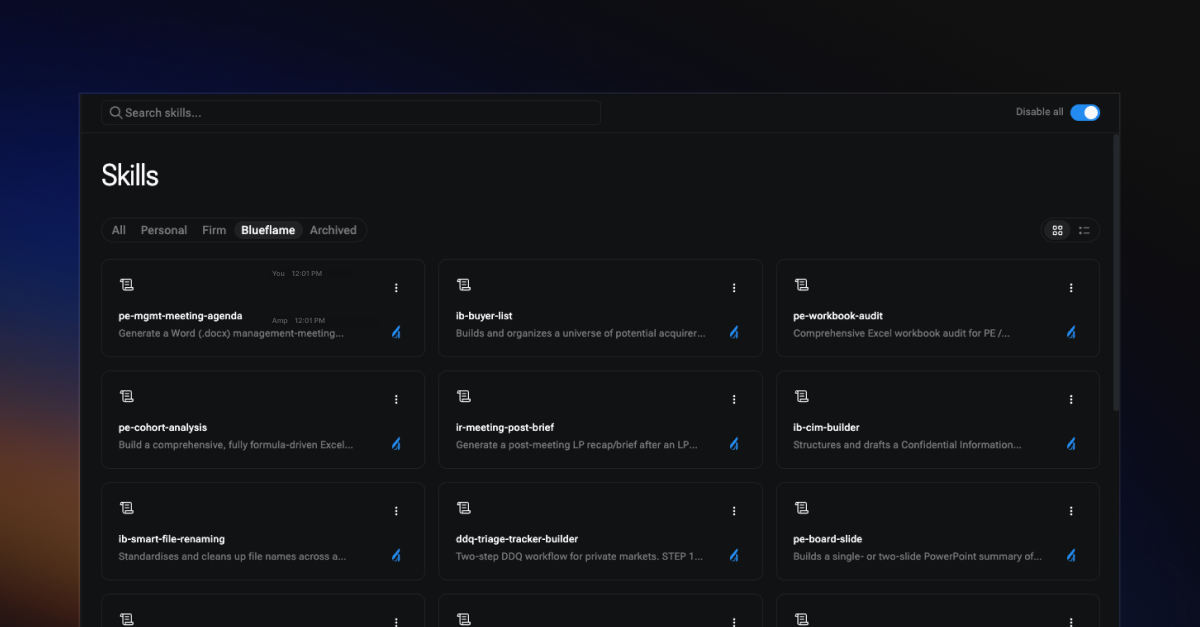
Multi-LLM chat/agent workspace for deal teams: "Amp" agent + "Blueprints" workflow templates (IC memos, LBO analysis, sourcing briefs) + enterprise search over data rooms/CRM/email + Excel add-in. Clients $8B–$65B AUM: L Catterton, CapVest, Lincoln International, Cinctive Capital.
Who uses it daily & what they do
- Analysts: CIM in → standardized summary and memo draft; plain-English Q&A across a data room
- IR teams: DDQ/RFP drafting from past LPAs/PPMs; LP letters
- Excel add-in: prompts inside cells pulling PDF data into model tables
- Private credit page: covenant tracking & exception flagging, quarterly reviews from compliance certificates, term benchmarking vs past deals, obligor-structure mapping from credit agreements
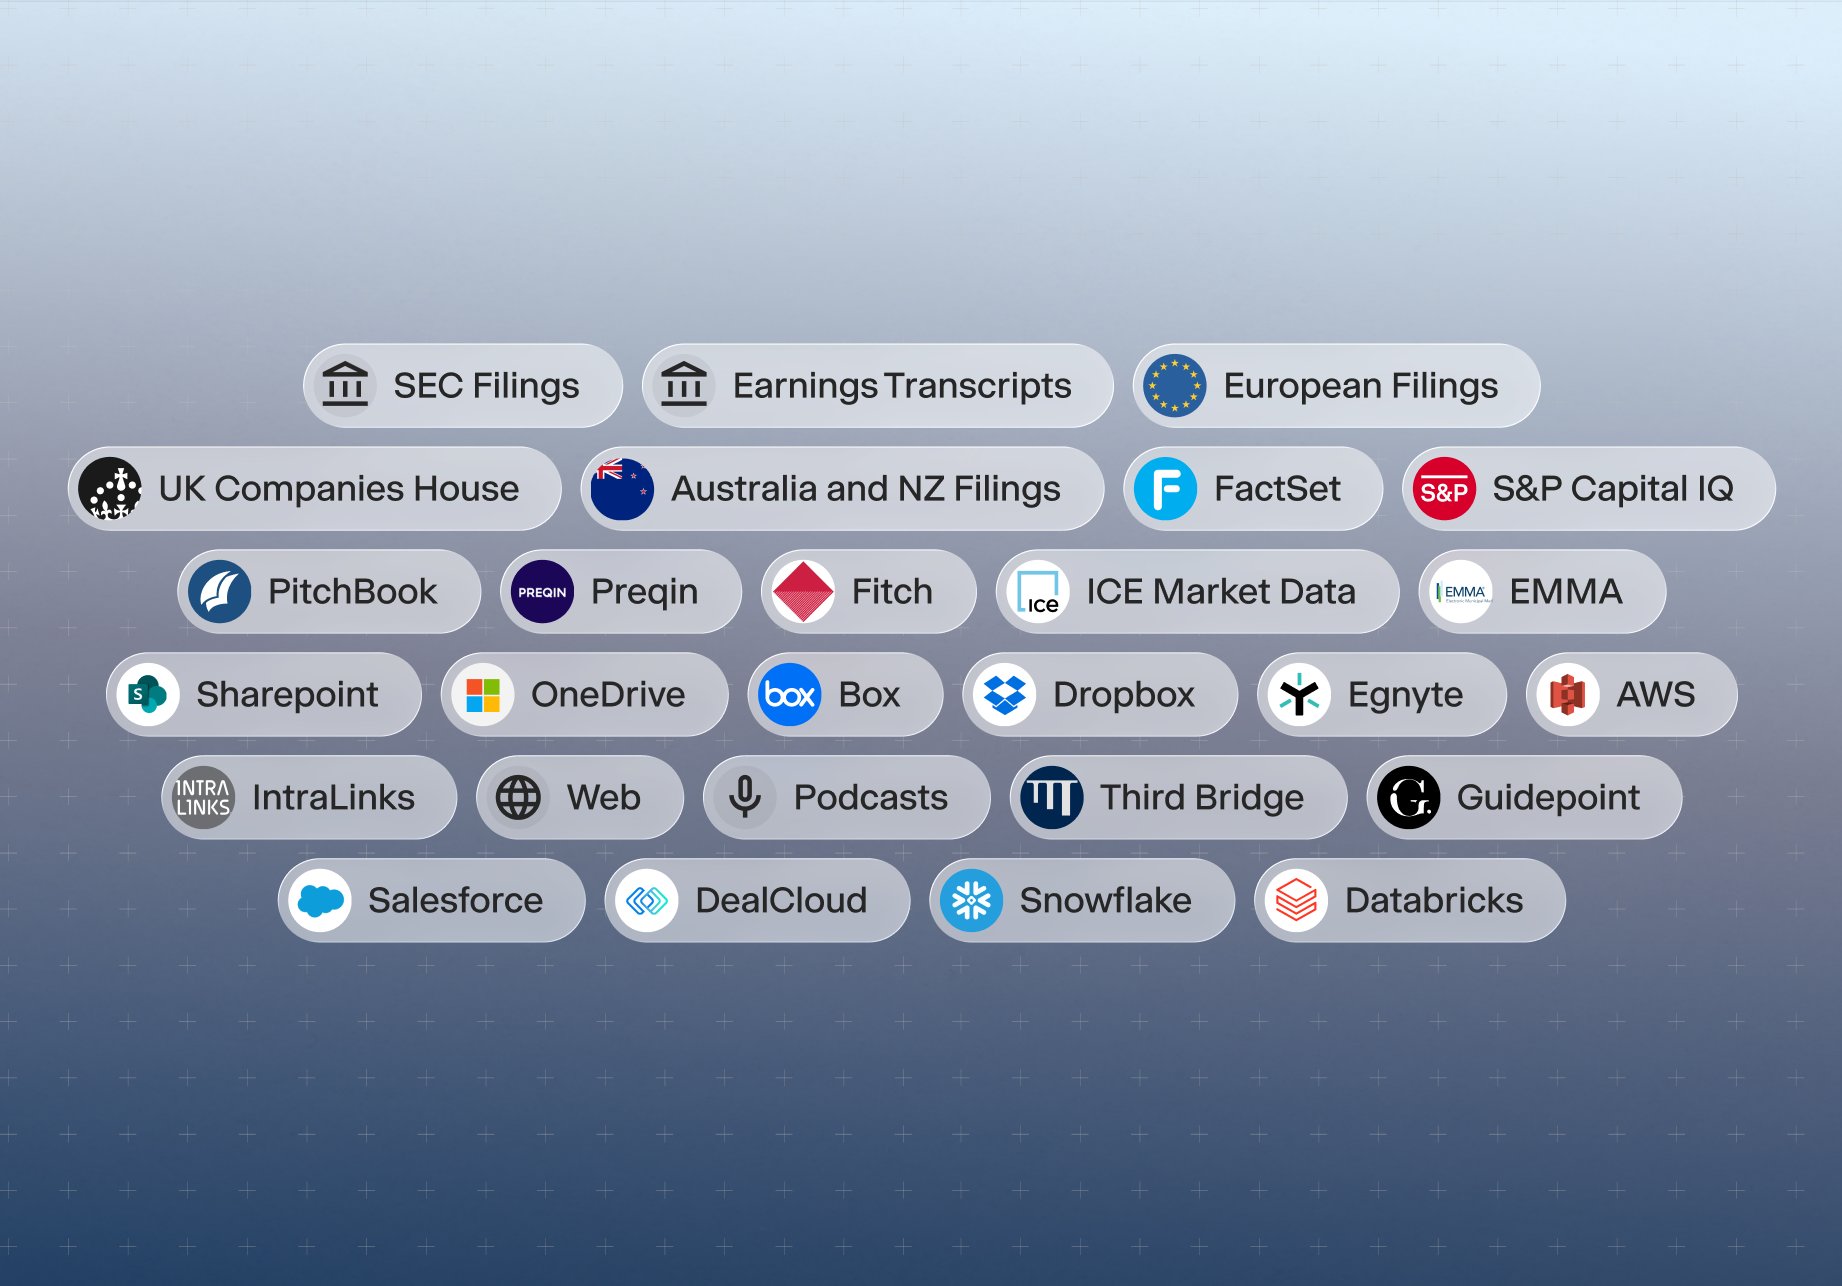
- Bidirectional Salesforce/DealCloud/Affinity; deep S&P Capital IQ integration; Datasite VDR real-time sync
Demos
Datasite VDR integration — permissioned data-room projects syncing into BlueFlame for AI analysis.
Joint Datasite + BlueFlame positioning video.
What users say
Bottom line
Post-acquisition it is the AI layer of a data-room vendor, optimized for transaction drafting speed inside Datasite's ecosystem. No owned data model, no credit model, no decision engine. Its notable patterns: Blueprints (reusable workflow templates) and integration breadth.
Chronograph Monitoring & LP reporting
Monitoring & LP-reporting leaderchronograph.pe · Brooklyn + London
What it actually is
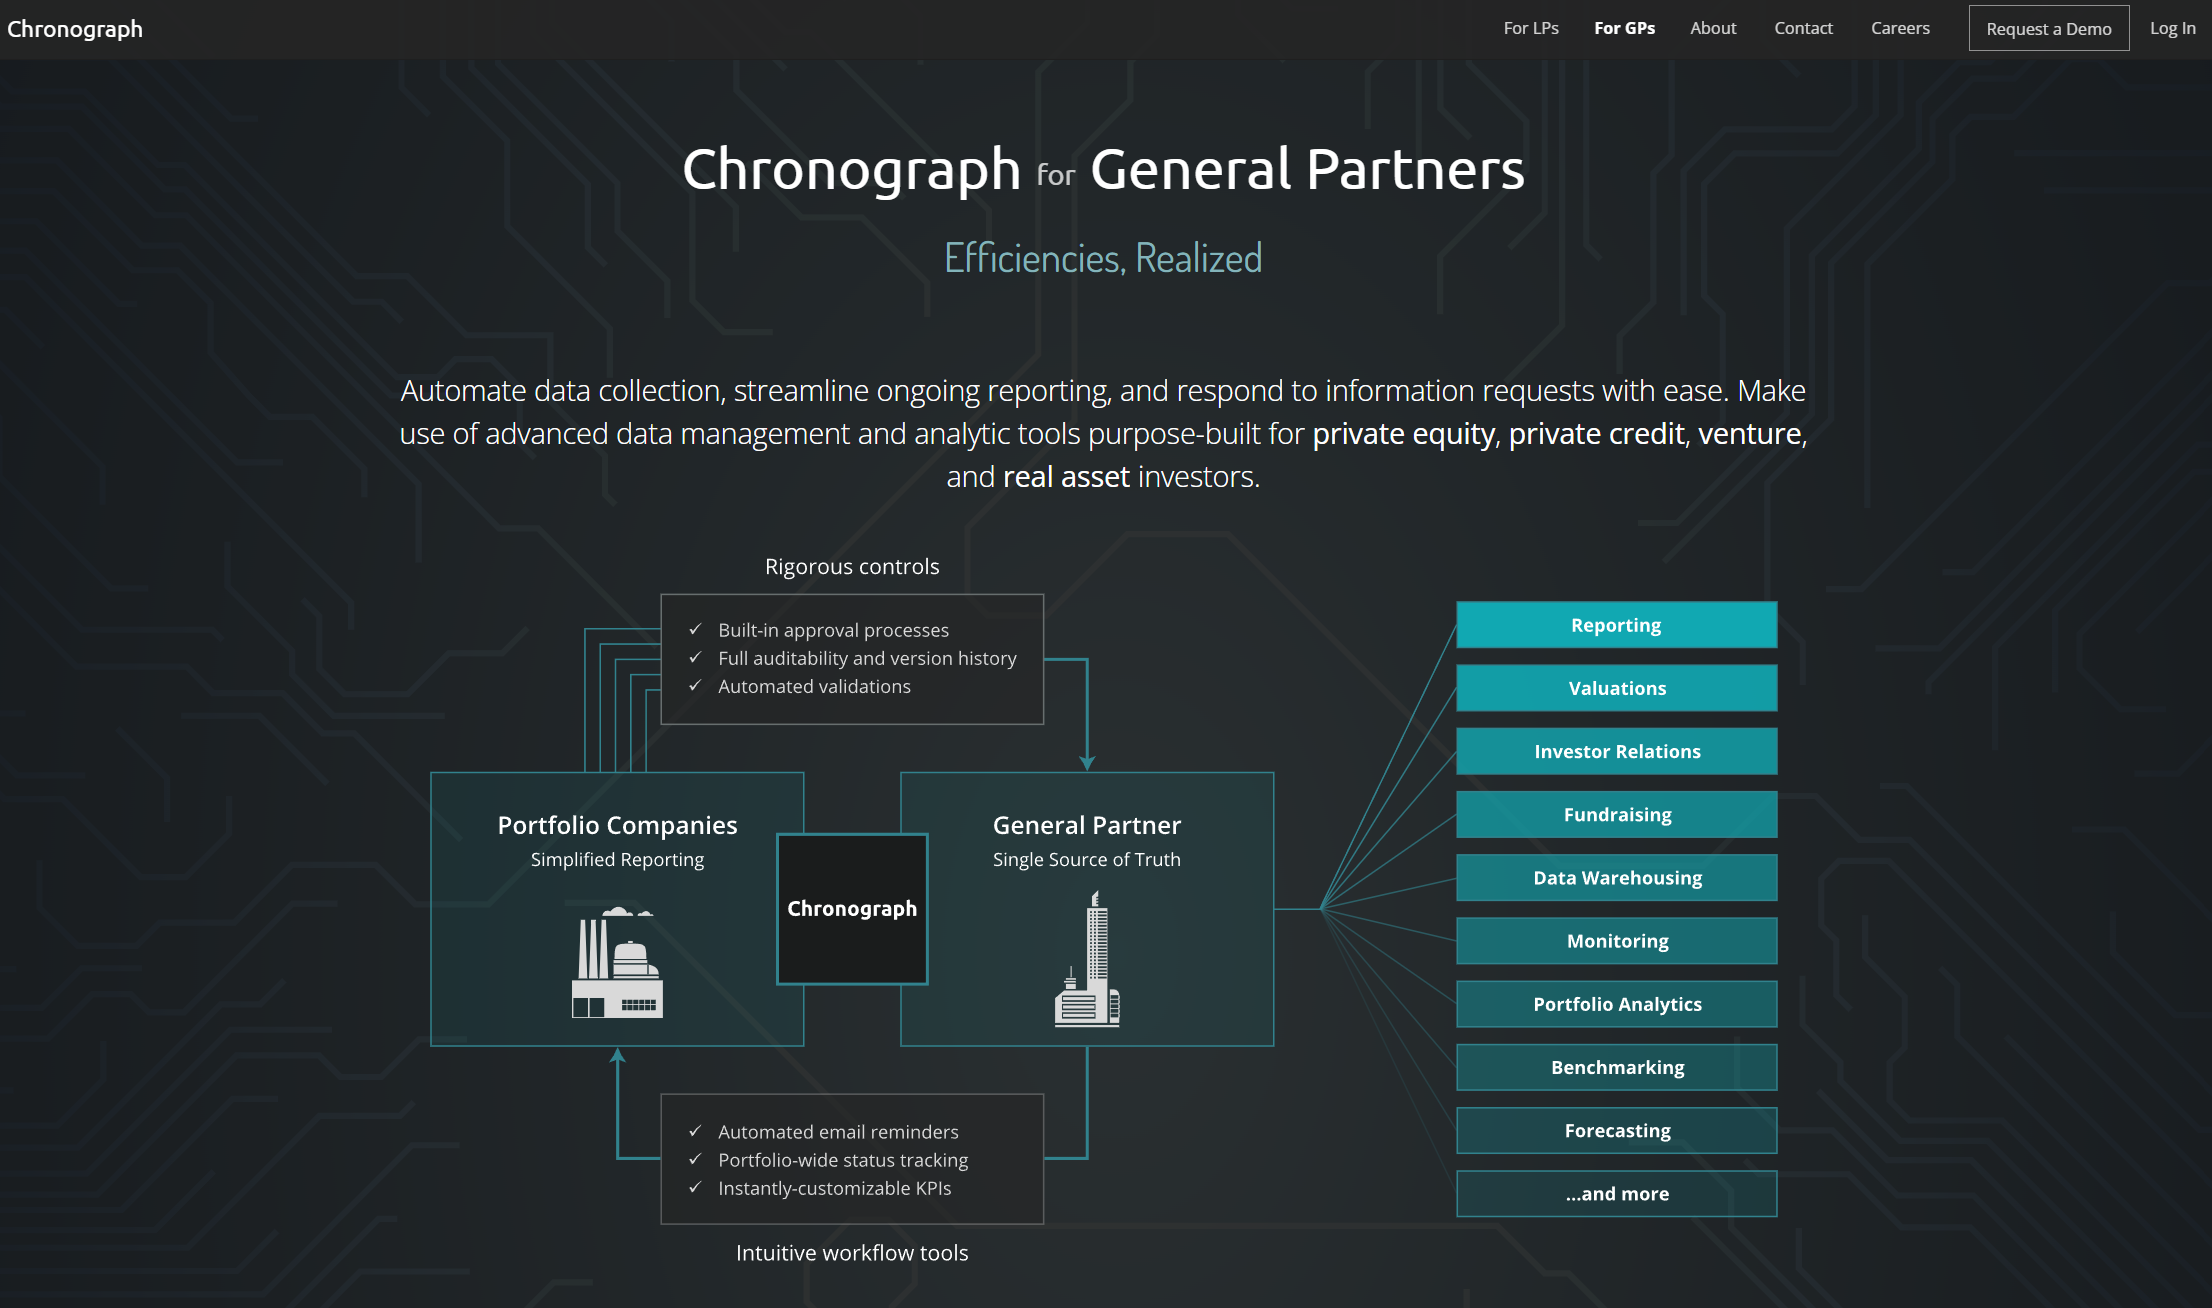
The portfolio monitoring, valuation and LP-reporting system for institutional private capital. Two products: GP (manager side) and LP (allocator side). Launched a dedicated private credit platform June 2026 — credit data model, covenant monitoring across debt tranches, borrower EBITDA add-backs validated against negotiated caps. Part software, part managed service (they staff data-ops analysts).
Who uses it daily & what they do
- CFO/fund-accounting, valuation, and IR teams (GP); portfolio analytics teams (LP)
- Set up quarterly collection: portfolio companies/borrowers get a portal + automated reminders, full audit history
- Validate submissions: variance checks; credit — add-back caps, covenant compliance certificates
- Run auditor-defensible quarter-end valuations; models stream alongside data
- Push-button LP reports: Word/Excel letters with dynamically linked numbers + version history
- LP product: GP quarterly PDFs digitized to structured data, every number click-traceable to source page
- ChronoAI natural-language queries; data out via Snowflake share, GraphQL, MCP into Claude/ChatGPT
Demos
CEO Charlie Tafoya on Nasdaq TradeTalks — data access in private markets (interview; no public product demo exists).
Third-party practitioners compare Excel vs. iLevel vs. Chronograph for monitoring (The Dashboard Effect podcast).
Bottom line
Strongest reference for the monitoring/LP-reporting layer — and now entering credit with $140M behind it. Its defining strengths: collection-portal machinery, click-to-source auditability, models-with-data for auditors, Snowflake/MCP data-out. Still post-investment only: no underwriting, no decision logic.
Quantpillar claimed: monitoring
Marketing, not productquantpillar.com · Irvine, CA + Vancouver
What it actually is
A borrower-side AI-CFO / 409A-valuation startup (dashboards for startup CEOs/CFOs, cheap fast valuations) that added lender-facing marketing pages around April 2026. The "QuantShield" monitoring pitch — covenant-drift alerts 60+ days early, credit-committee packs — exists only as website copy. The "Portfolio Health Monitor" on the lender page is a static HTML mockup, not a product screenshot. No demo, no lender customers, no product page, no funding, no team behind it.

Only site visual recoverable (via Wayback — live site blocks fetching). Their terminal page is the one interactive surface.
Bottom line
Not a viable vendor today. The one interesting idea: a borrower-verified data layer feeding lender monitoring ("Trust Link"). Someone will build this properly; it isn't them today.
Auquan AI credit-workflow agents
Credit-workflow agentsauquan.com · London + NYC (eng: Bangalore)
What it actually is
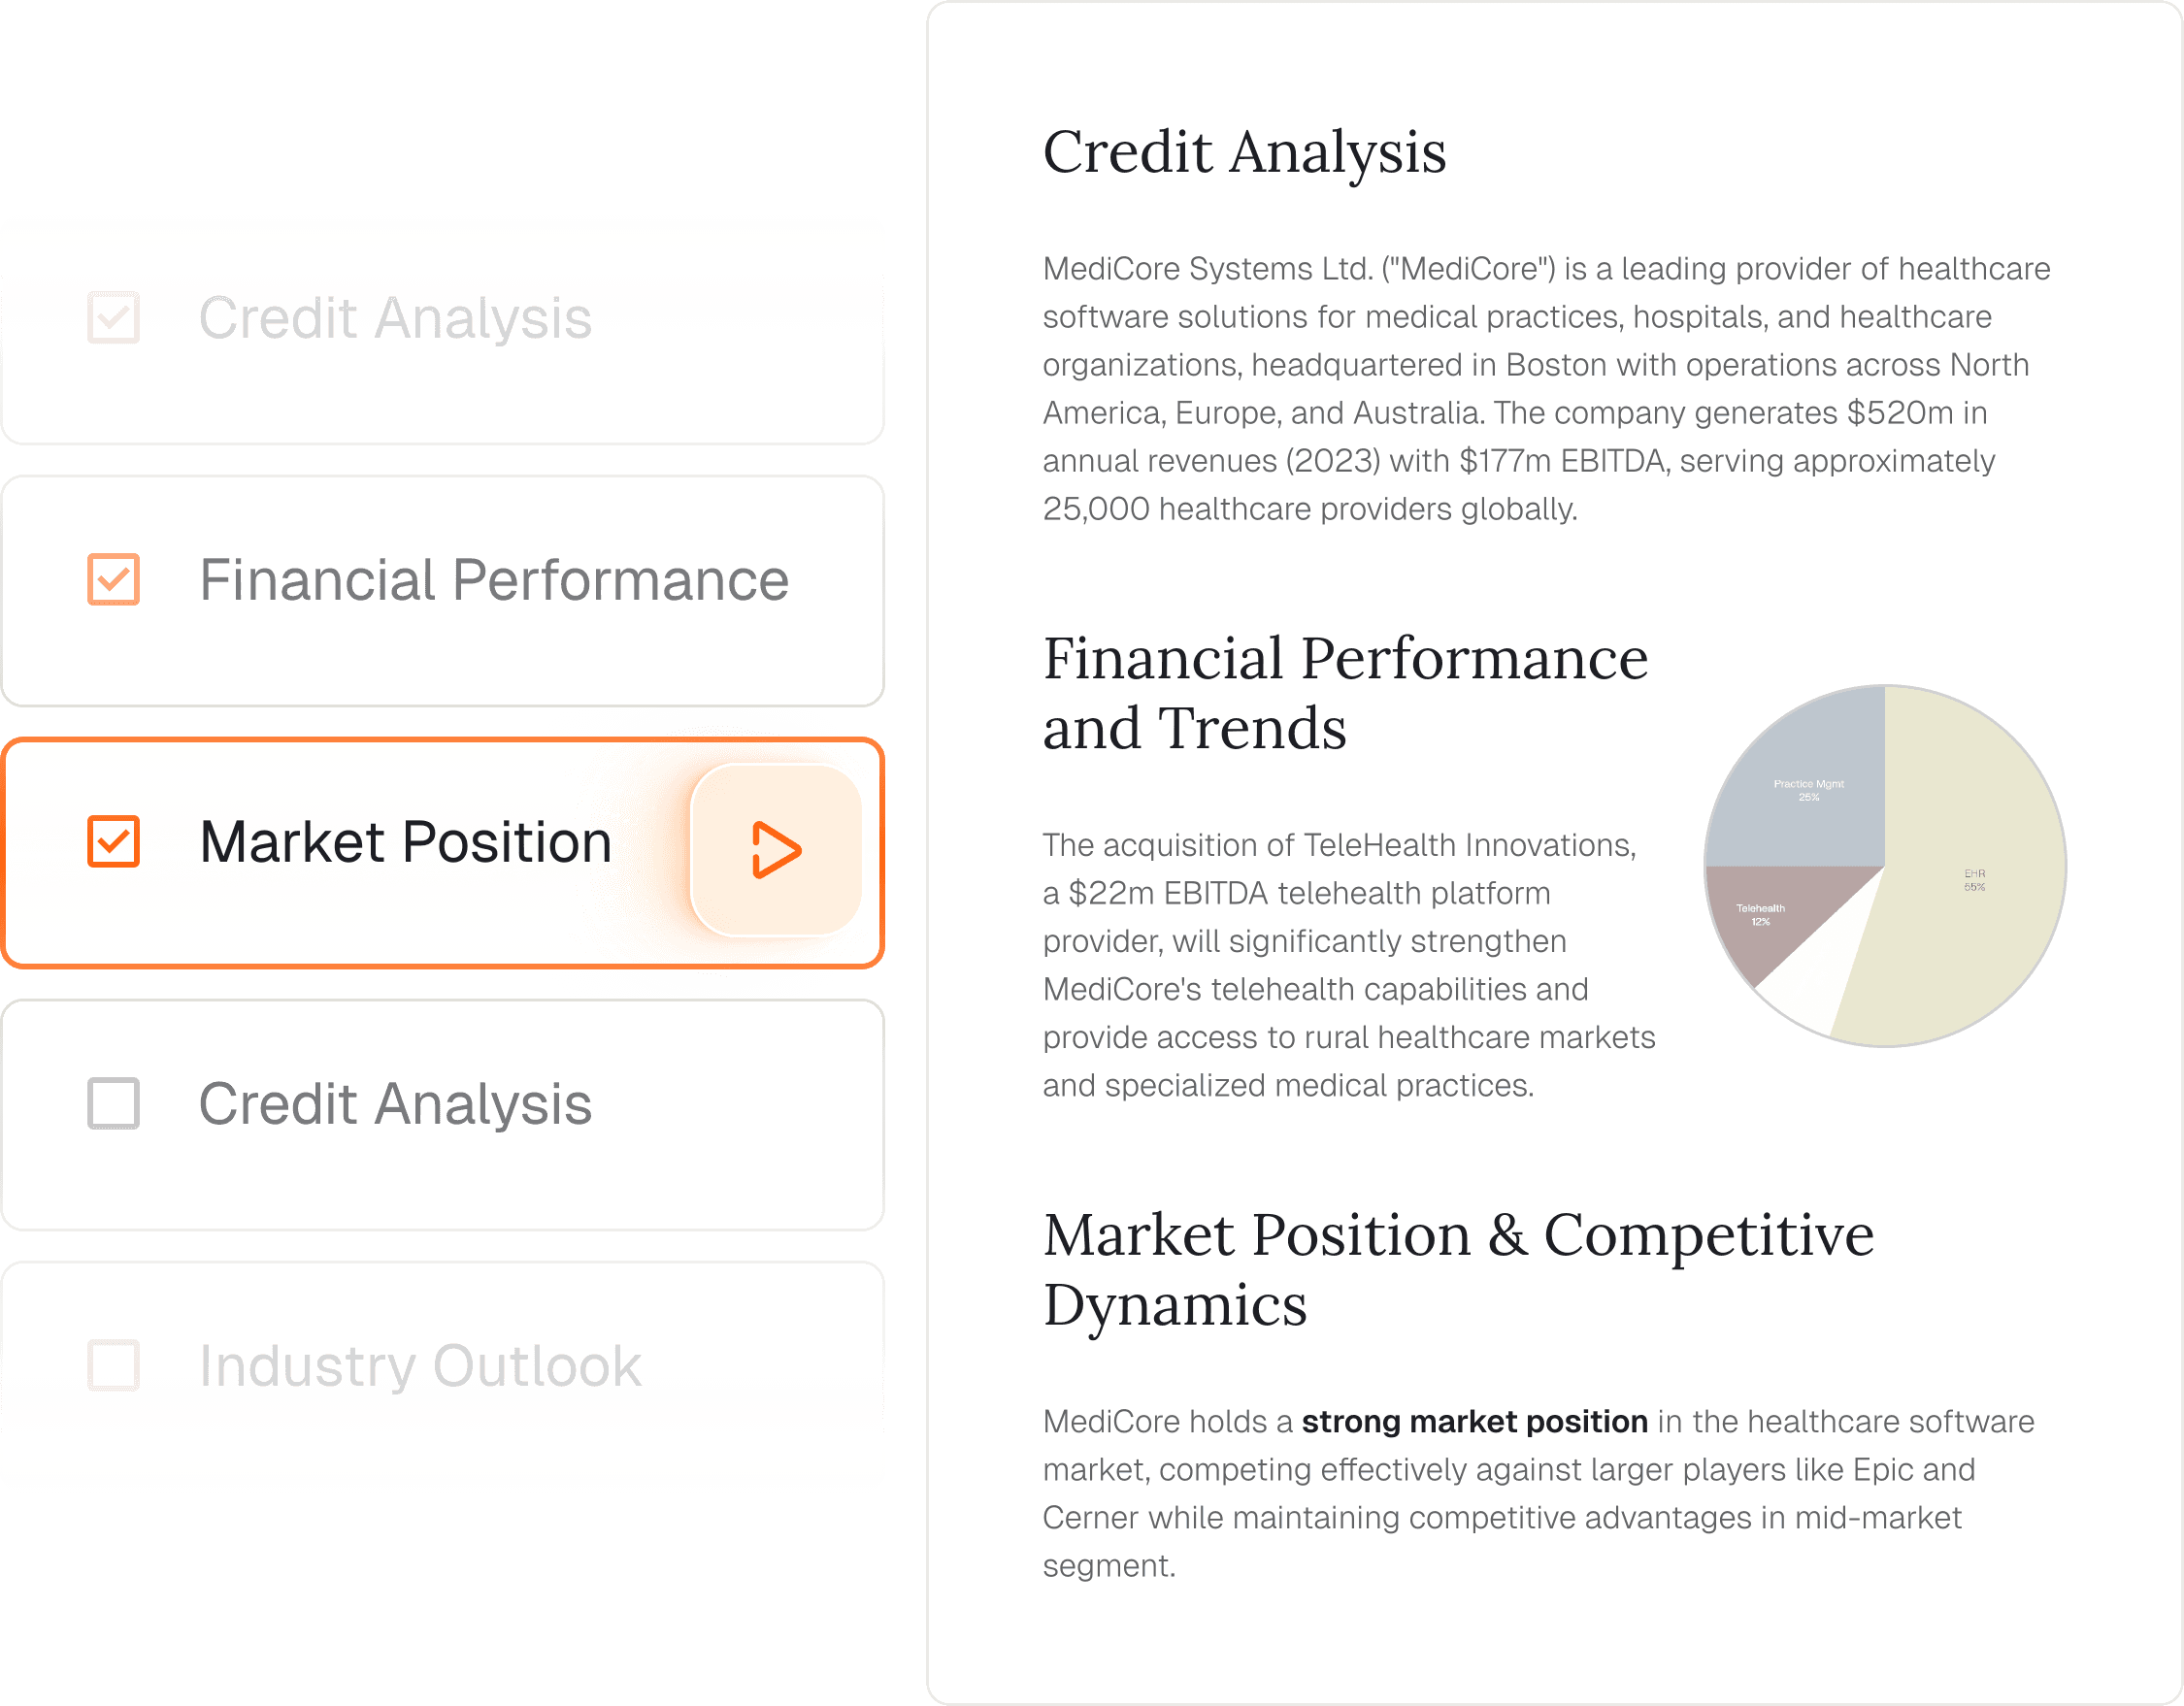
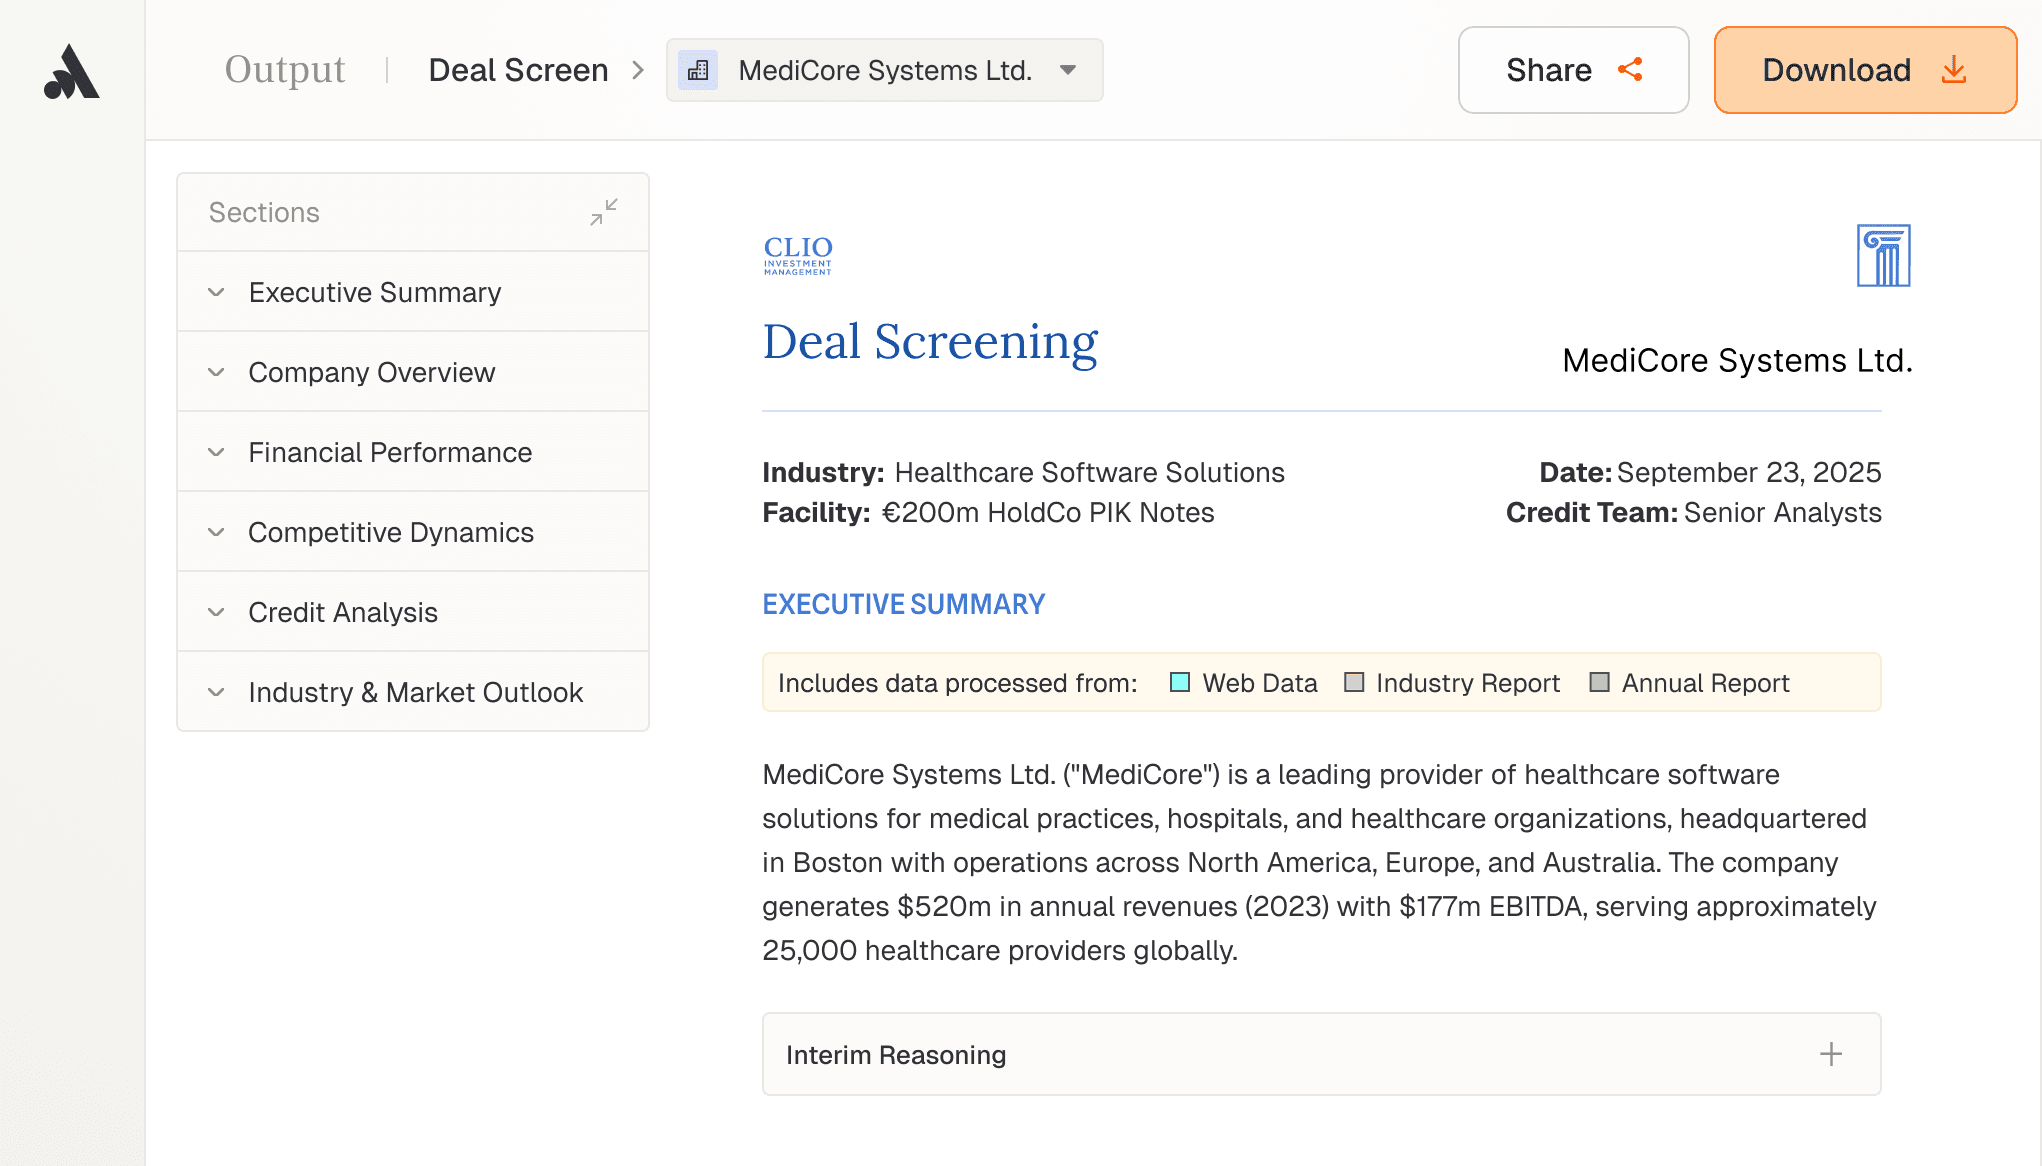
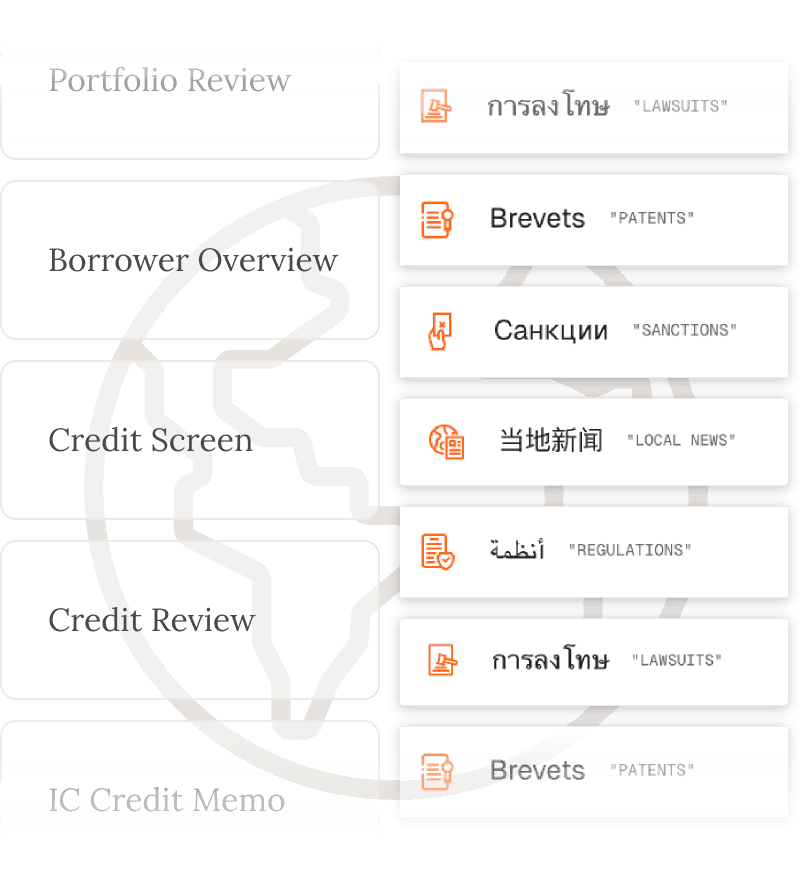
Autonomous "deep work" agents that run whole document workflows end-to-end. The Credit Agent (Sept 2025) covers the full credit workflow: deal screening with red-flag scoring, borrower financial-health checks, IC memo generation in the firm's own template, covenant monitoring with alerts, portfolio reviews, LP/regulatory reporting. Gartner Cool Vendor 2025. Lives inside Microsoft 365.
Who uses it daily & what they do
- CEO's own words: "most users are juniors — analysts using it to write reports more quickly"
- The signature flow (seen in the demo video below): dump messy borrower docs → agent proposes an editable plan-of-action (memo sections, each with its own sub-plan) → runs ~70+ searches across internal docs + subscriptions + 2M public sources → returns a cited memo in firm template
- Deal screening: 2 days → 30 min (claim); portfolio reviews at one bank: a week → 10 min (claim)
- Risk Agent watches 2M+ sources, 76 languages, for early warnings on held names
Demos
FINTECHTALK (Mar 2025) — CEO Chandini Jain demos the messy-docs→credit-memo flow with the plan-of-action screen. Best public demo evidence; full demos are sales-gated.
Bottom line
The most credit-workflow-complete agent vendor. But it is document-in / prose-out: no loan-level data model, no decision engine, no system of record, no LP portal. Per-document pricing tells you what it is: a report factory. Enterprise ICP — lower-mid-market lenders are not who it's built for.
Keye Diligence automation (PE)
Deterministic-math architecturekeye.co · NYC
What it actually is
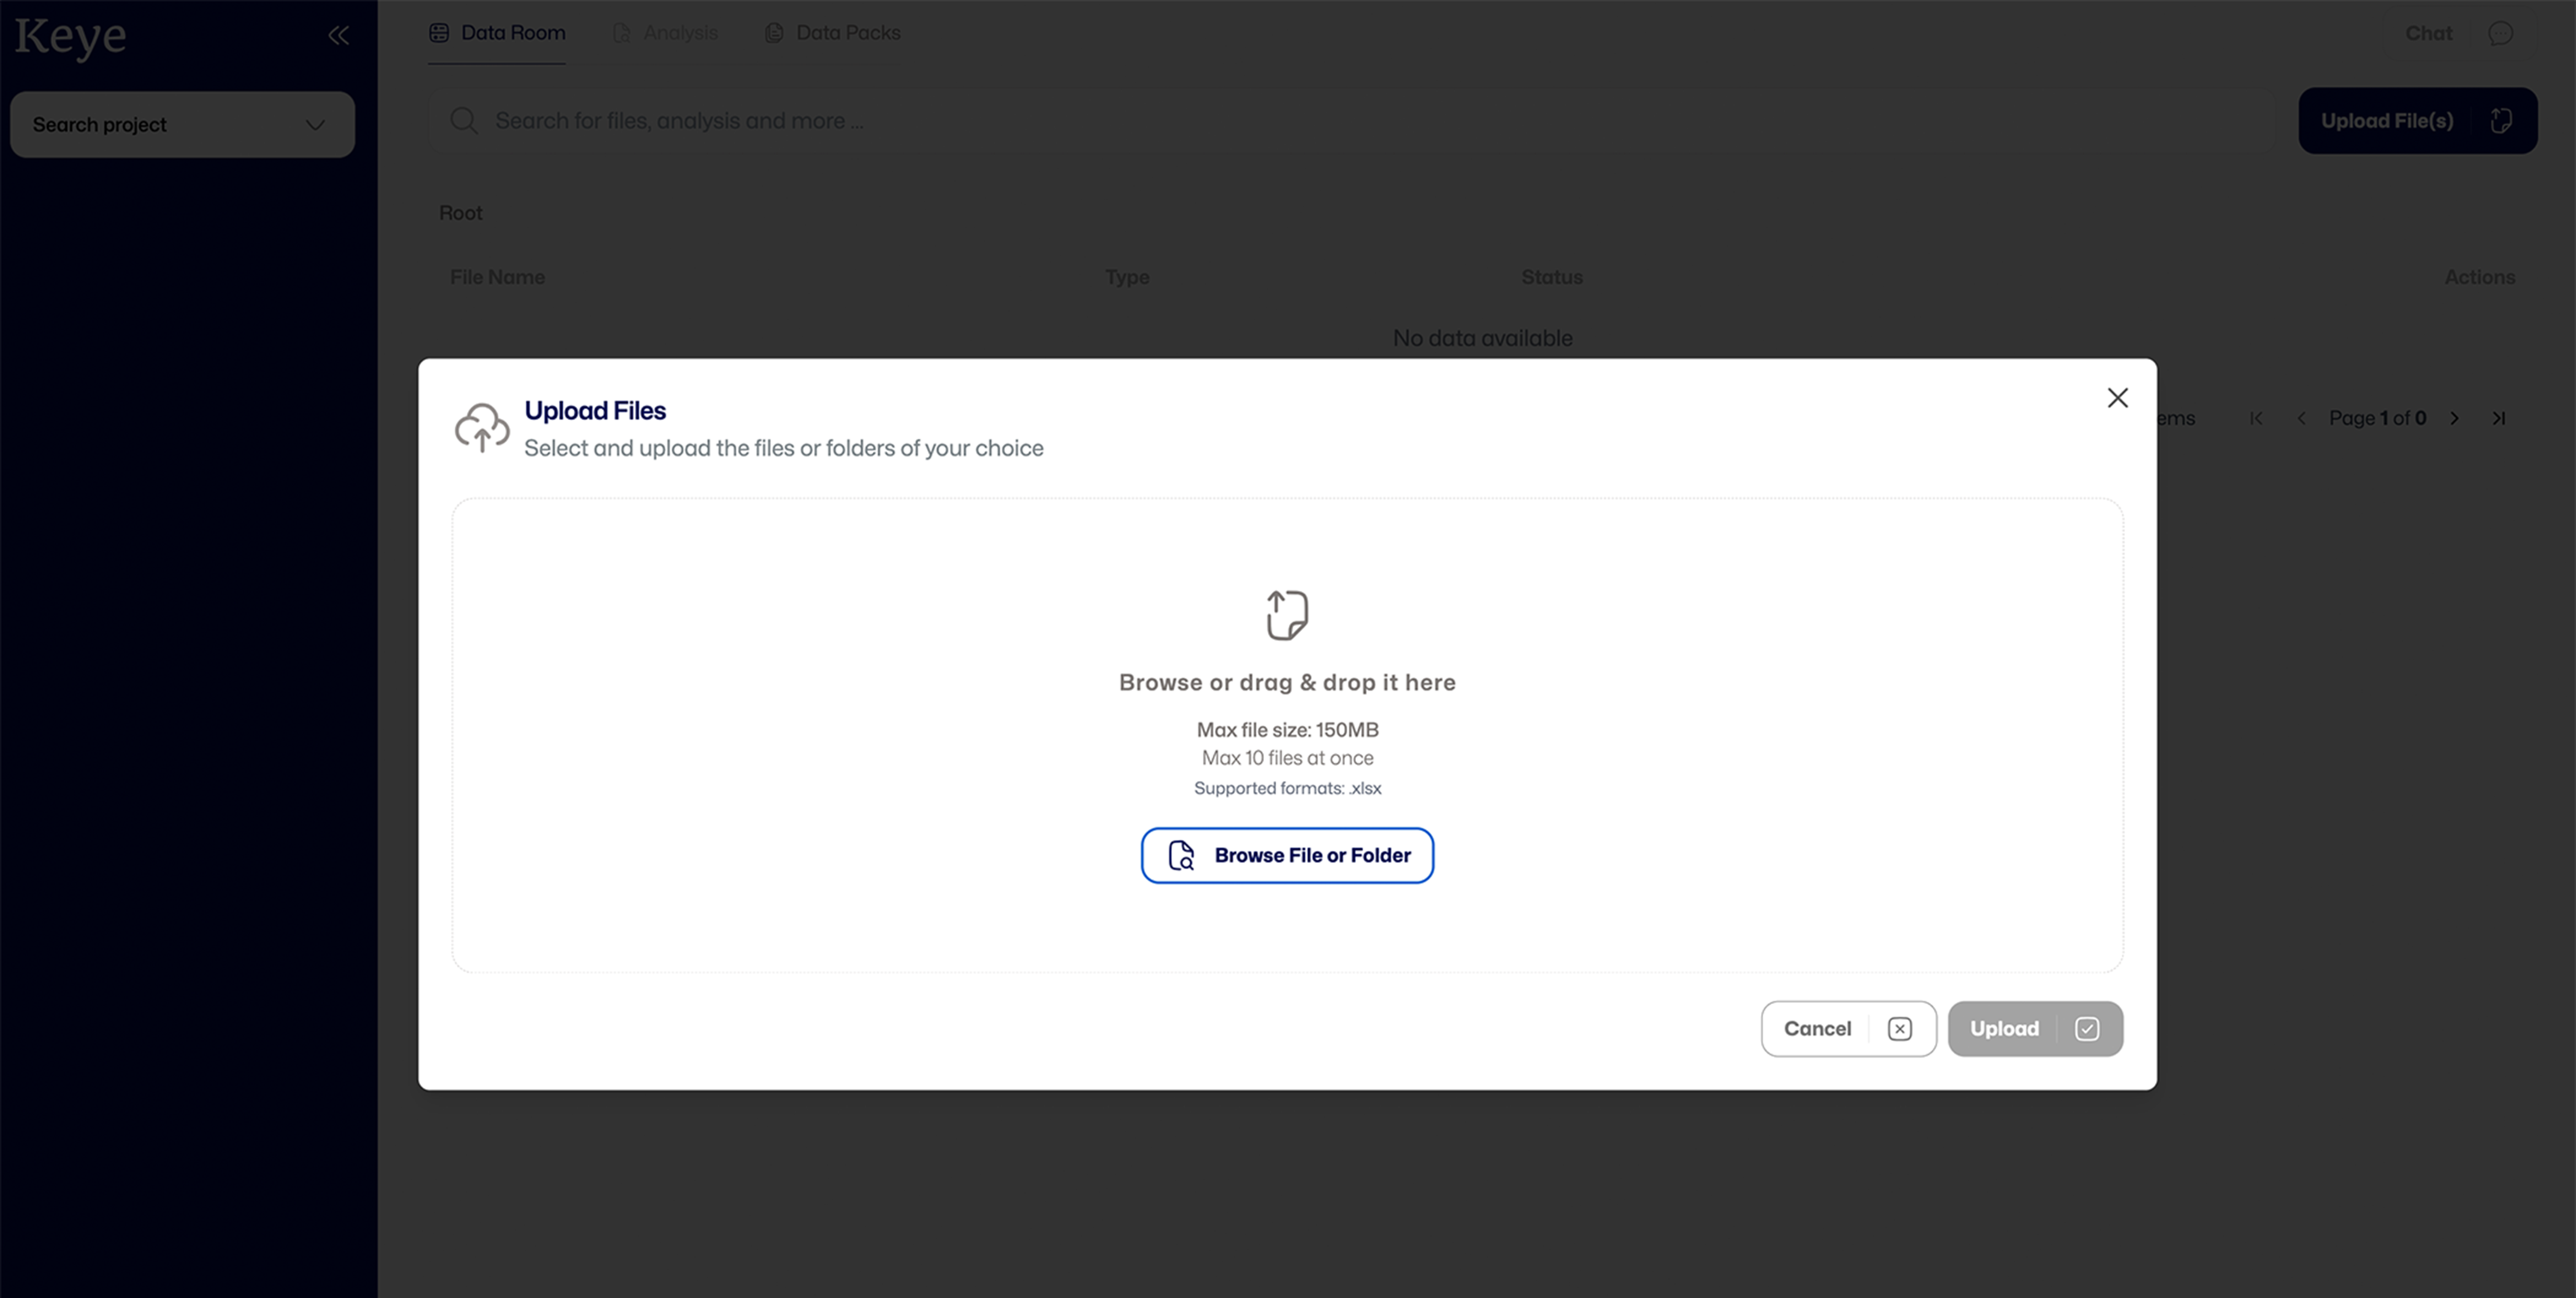
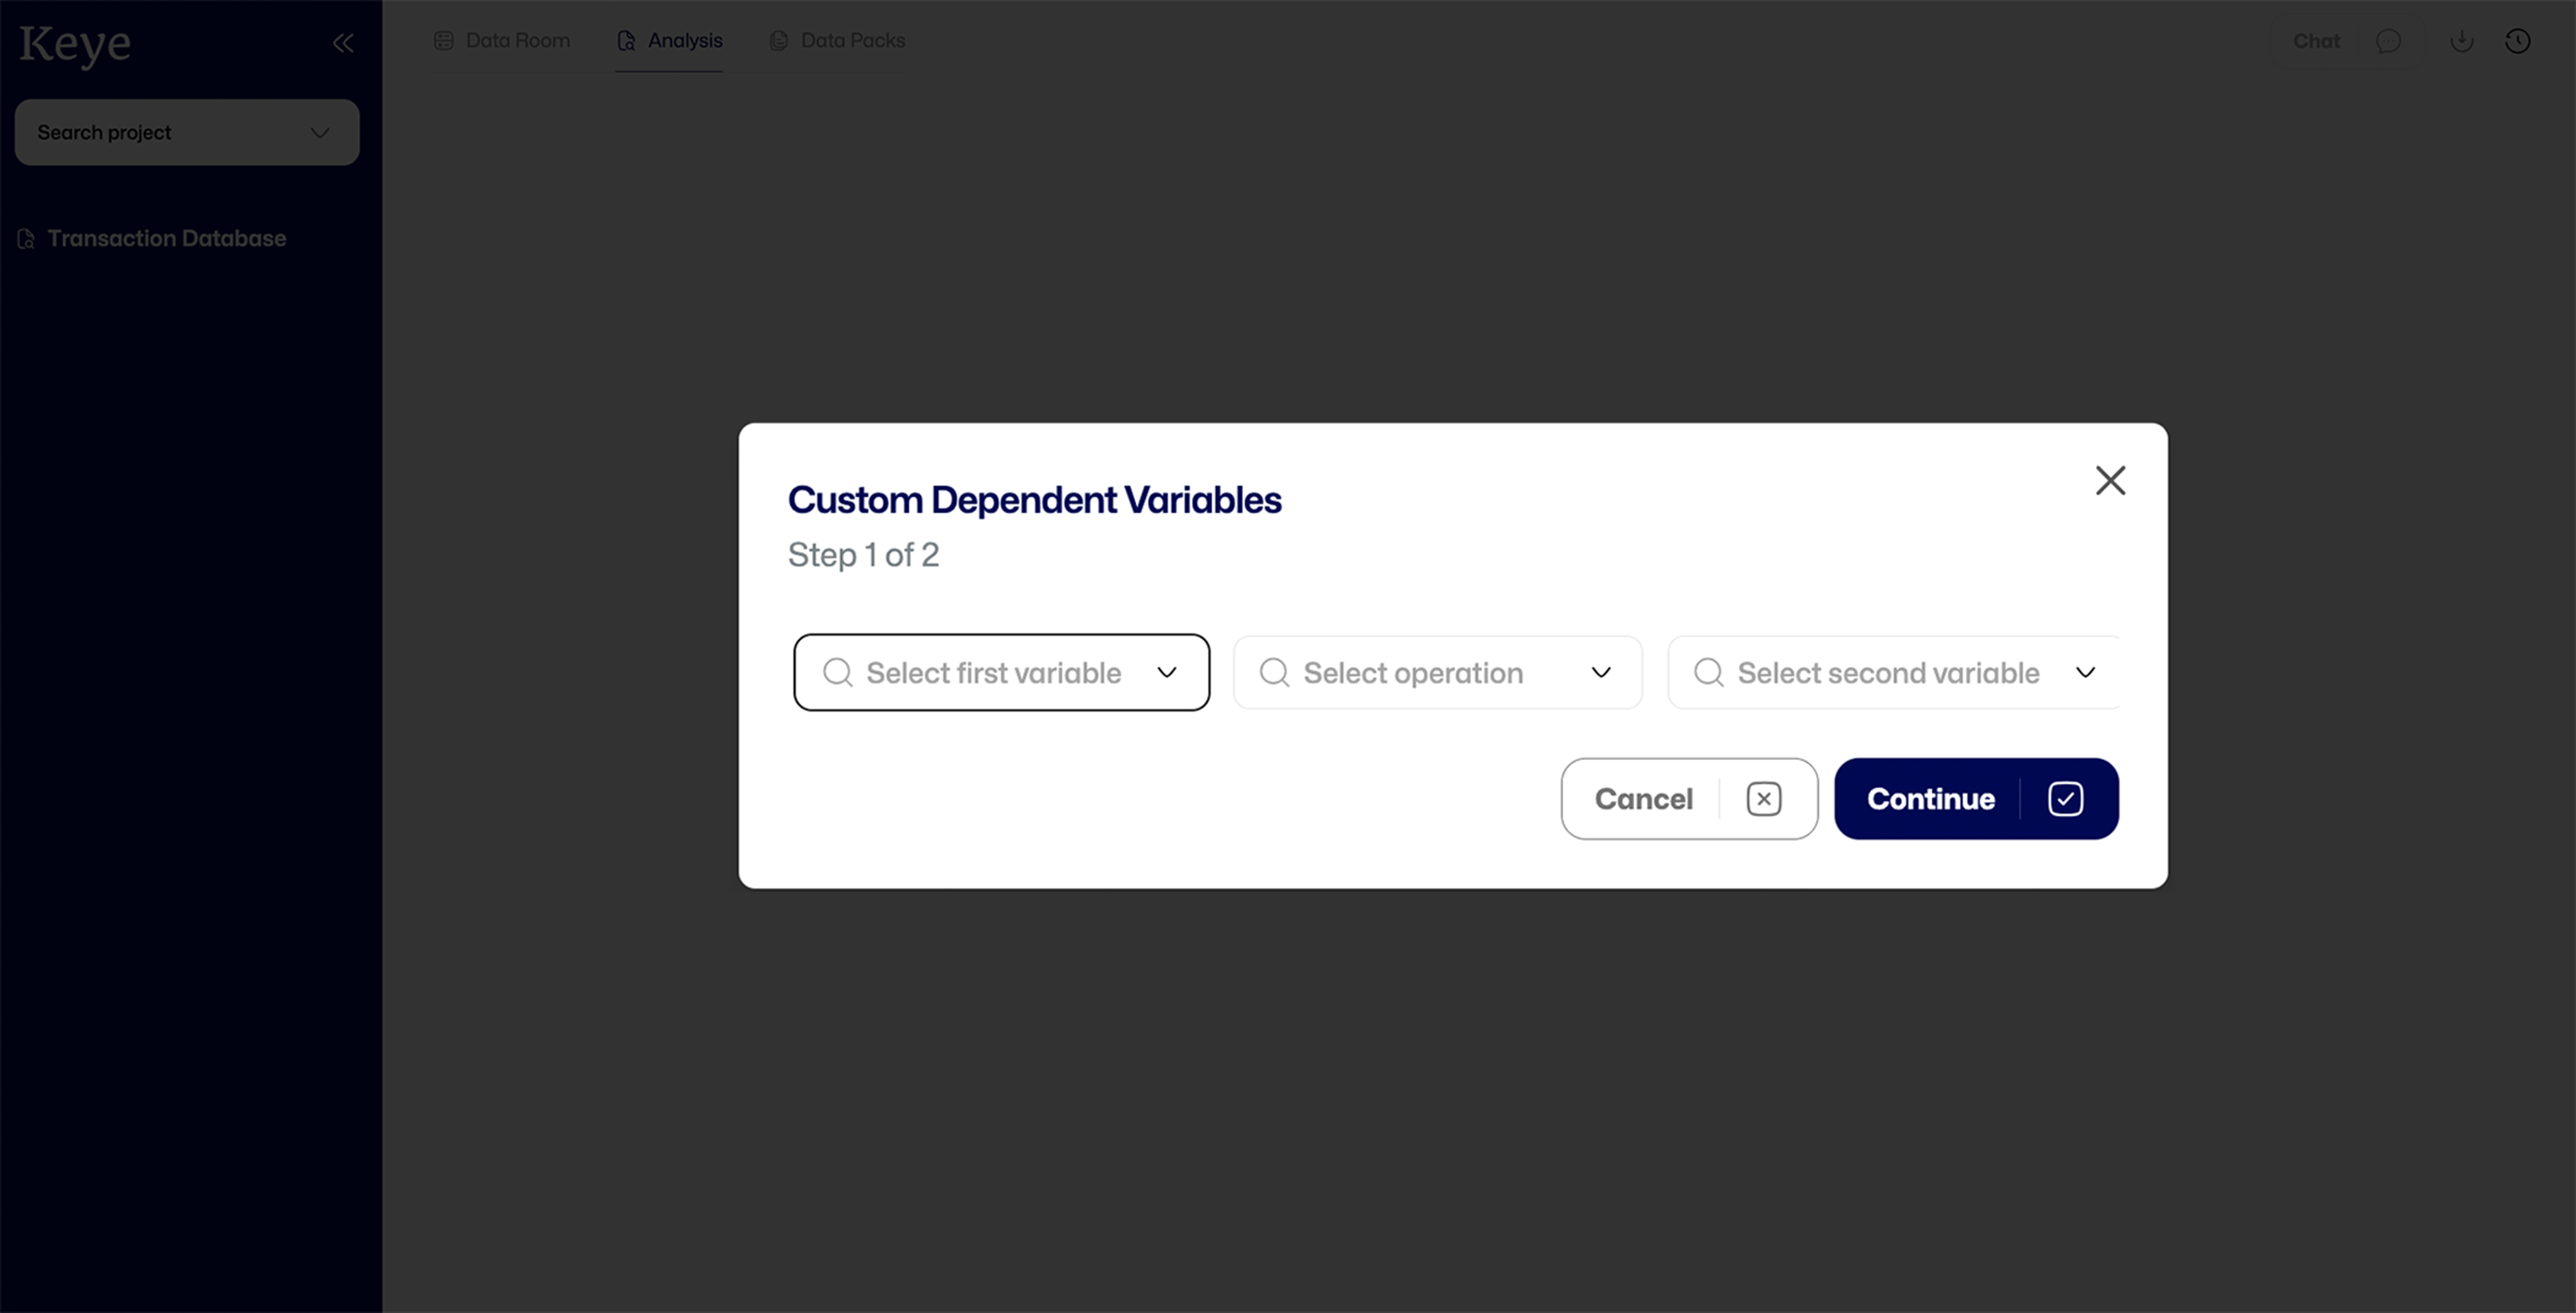
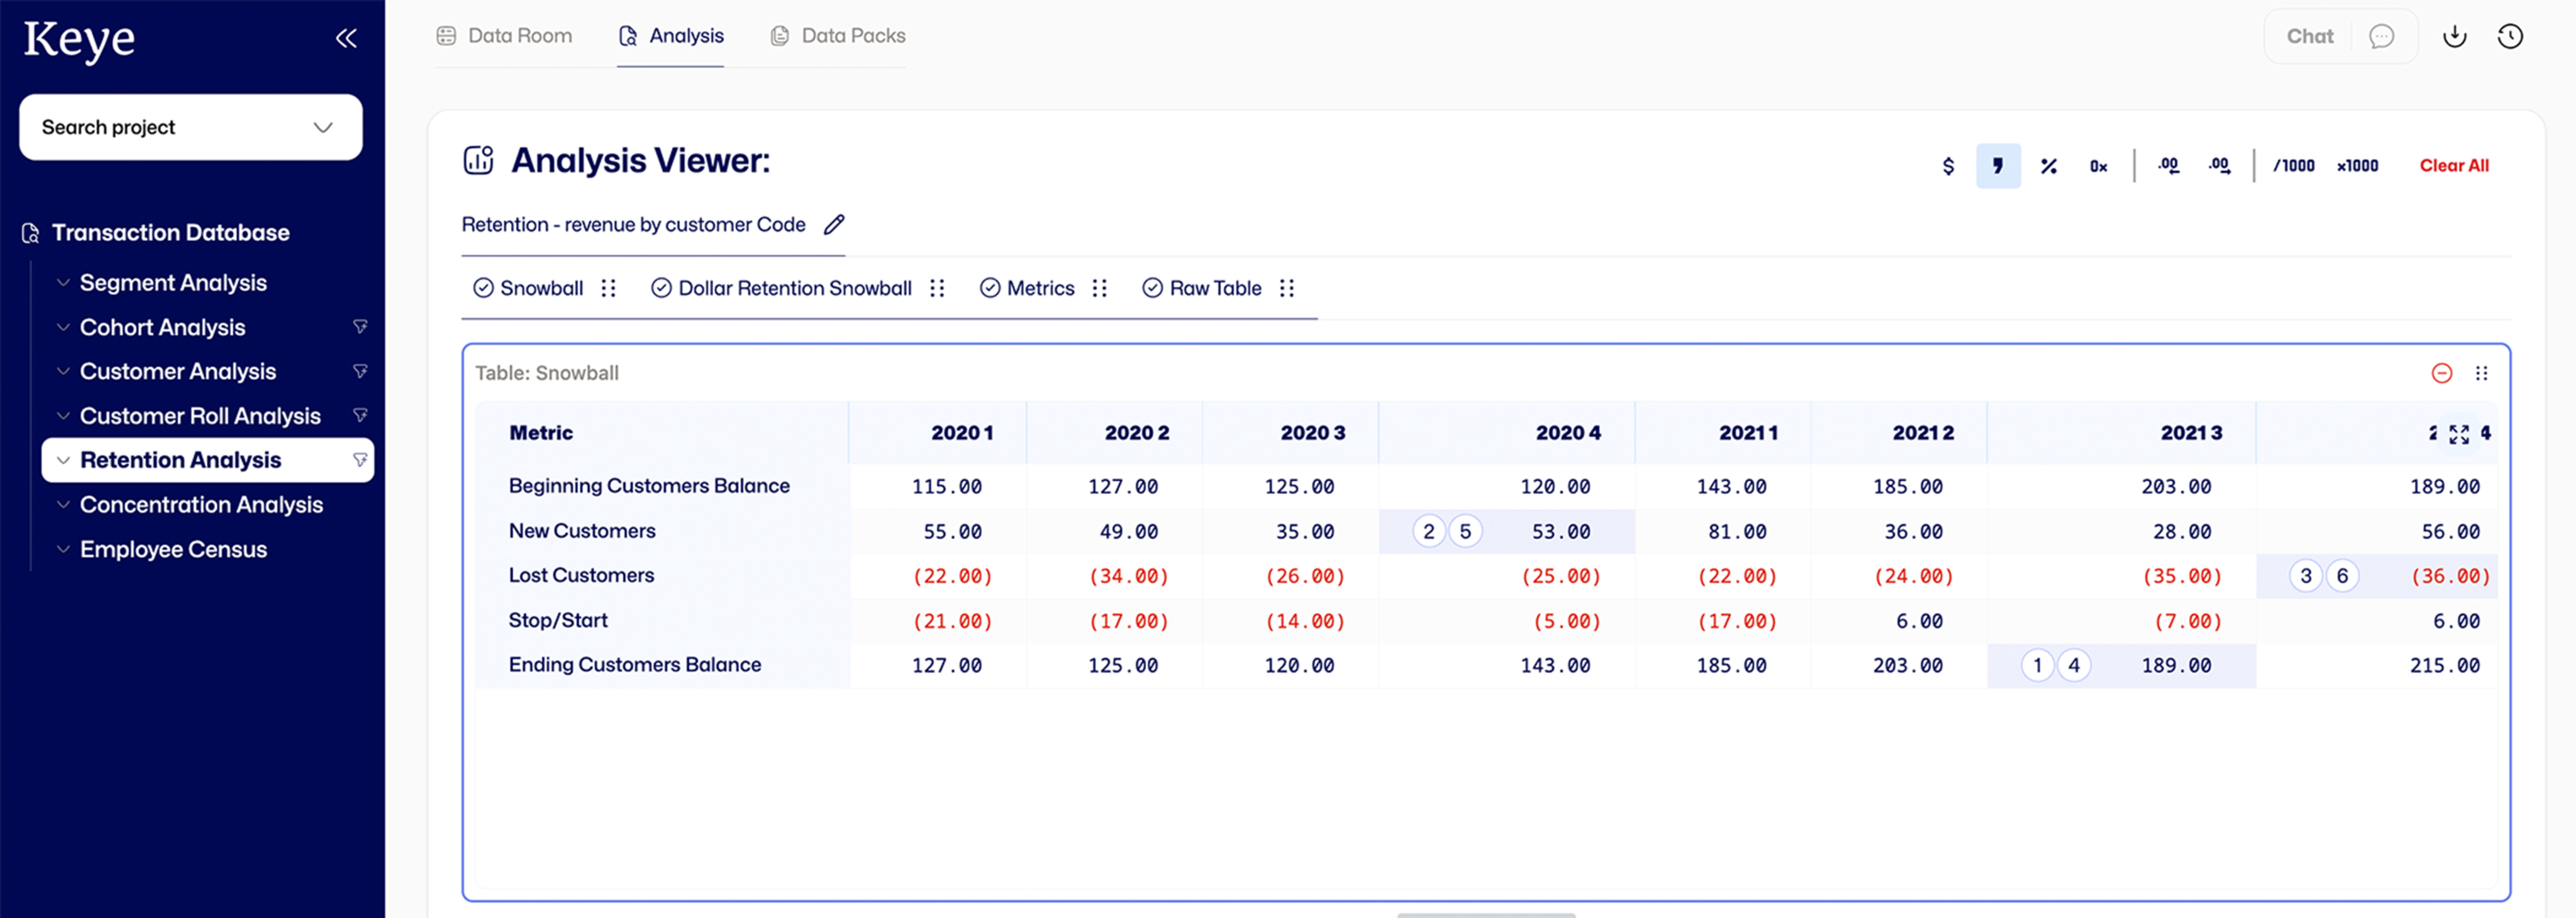
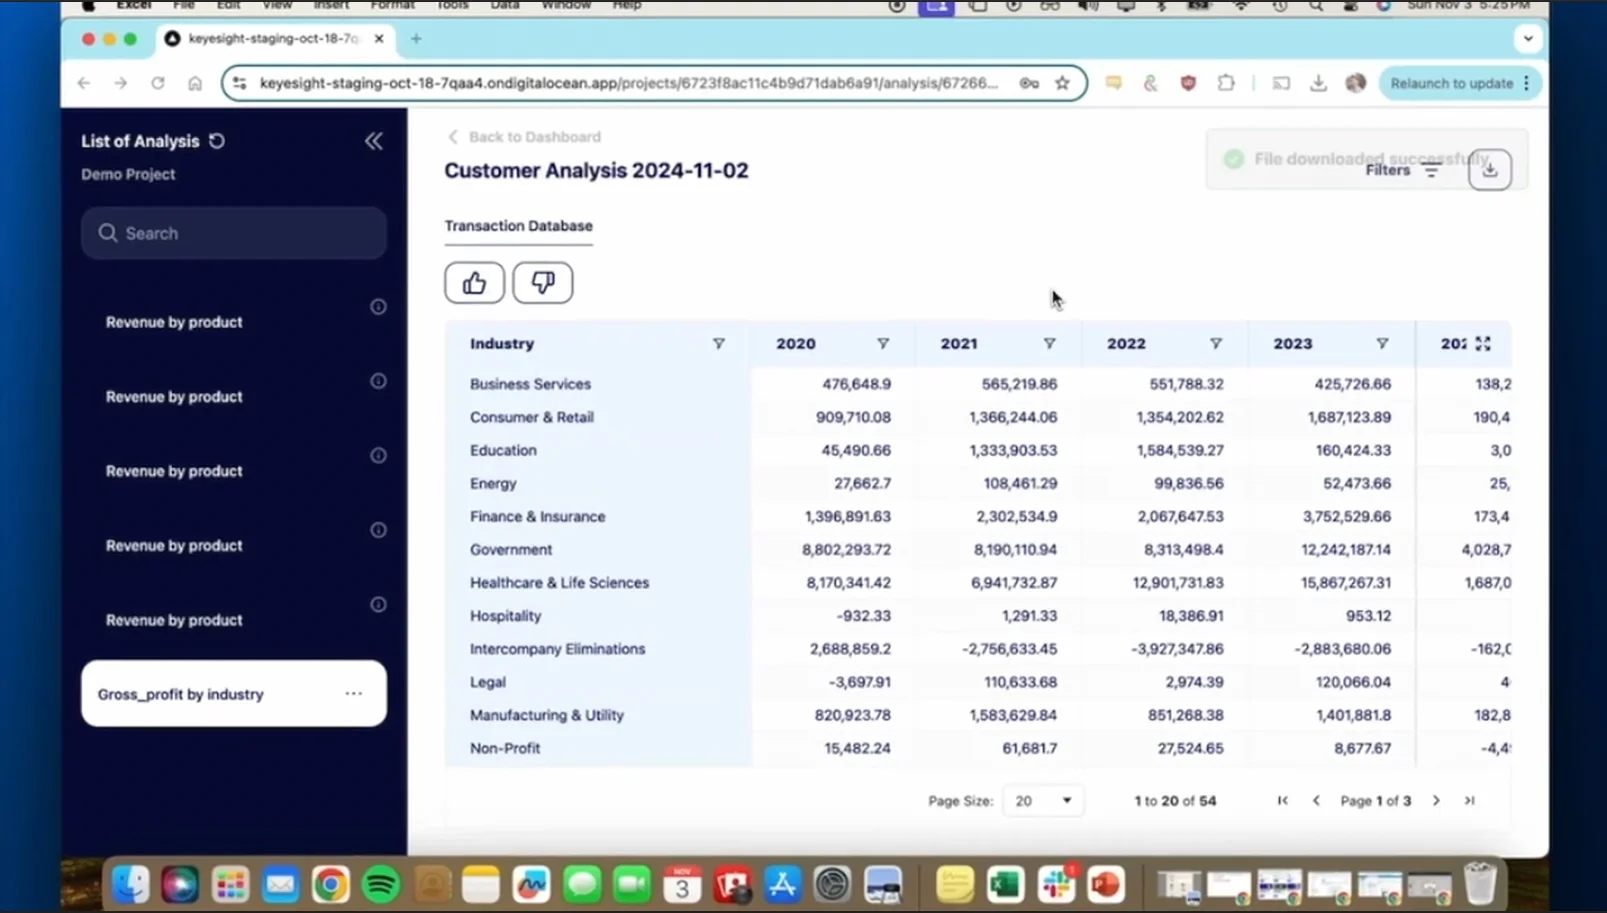
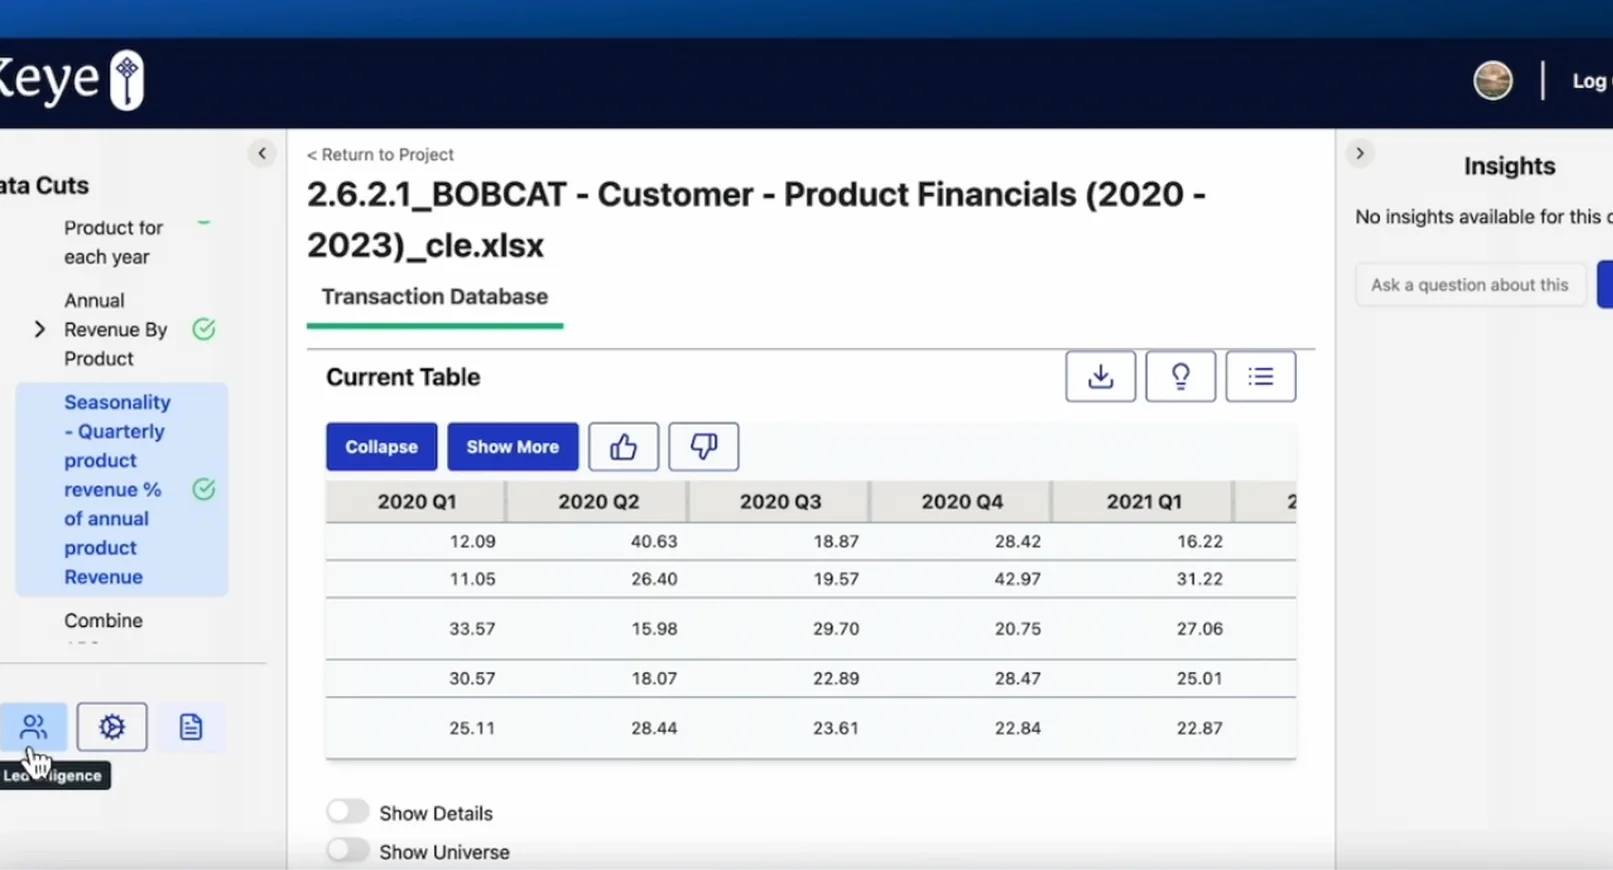
An "AI analyst" for PE due diligence built on deterministic computation: the LLM interprets intent, but every analysis runs as auditable code/formulas ("Odin" co-pilot, Jan 2026). Data room in → cohort retention, price/volume, margin bridges out → Excel export with live formulas, no hardcoded cells, every number traceable to source.
Who uses it daily & what they do
- Analysts/associates: upload VDR → structured data pack → standard diligence analyses auto-generated
- Partners: kill bad deals earlier ("80% understanding of a deal in minutes"); claims 5+ days saved/deal, 40% more deals per analyst
- Benchmark the live deal vs the firm's past deals; ask ad-hoc plain-English analytical questions
Demos
Official Loom demo — "Unlock your Due Diligence Process" (from the YC launch).
Founder podcast — Rohan Parikh (ex-Natixis IB, S&P credit).
What users say
Bottom line
Zero credit functionality today — "built exclusively for private equity." The notable piece is the architecture: deterministic, code-executed math with formula-level auditability, an approach that would transfer well to credit underwriting if they ever go there.
F2 Credit-first "OS" (Arc spinout)
Most credit-native of the ninef2.ai · NYC (expanding SF + London)
What it actually is
The most credit-native platform of the nine: a credit-first, Excel-native "AI operating system for private markets" covering screening → underwriting → IC memos → portfolio monitoring. Spun out of Arc Technologies (CEO Don Muir). Growth: 650% YoY users, 15,000+ deals analyzed. It explicitly positions against Hebbia as "vertical deal execution vs horizontal document search."
Who uses it daily & what they do
- Credit analysts / bank underwriters: borrower PDFs → spread financials → live multi-sheet Excel models with real formulas, sensitivities, scenarios (claims 95.25% on SpreadsheetBench; handles 20MB+ workbooks with circular refs)
- Audit Mode / Databook: click any number → formula chain → source page (their wedge)
- Screening: inbound CIM → tagged summary benchmarked against pipeline history
- IC memos in firm templates; precedent queries ("have we seen this covenant before?")
- "Adam" agent (Jun 2026): decomposes a deal, delegates to sub-agents, ~60-min autonomous runs
- Monitoring (covenants, exposure, borrower reporting): announced, partly still "launching soon" — their least mature module
- Case studies: RevTek 2x deal throughput; Decathlon 2,753 files → 128 reports, −50% diligence grunt work
Demos
"Introducing F2" launch video (Sep 2025) — data room → analysis → memos, "data room to decision 60% faster." The "F2 2.0" video (Nov 2025) has been taken off YouTube; real demos are gated "on your own deal history."
What users say (vendor-sourced only — no independent reviews exist)
Bottom line
Miscategorized as a diligence tool — it is an operating-system play (credit-first + Excel-native + auditability wedge at ~$120K ACV). What it does not have yet: a decision engine, risk logic calibrated on lived lending outcomes, or mature monitoring/LP reporting — and it is generic across lenders rather than built around any one fund's historical data.
Hebbia Document intelligence (Matrix)
Document-intelligence leaderhebbia.com · NYC
What it actually is
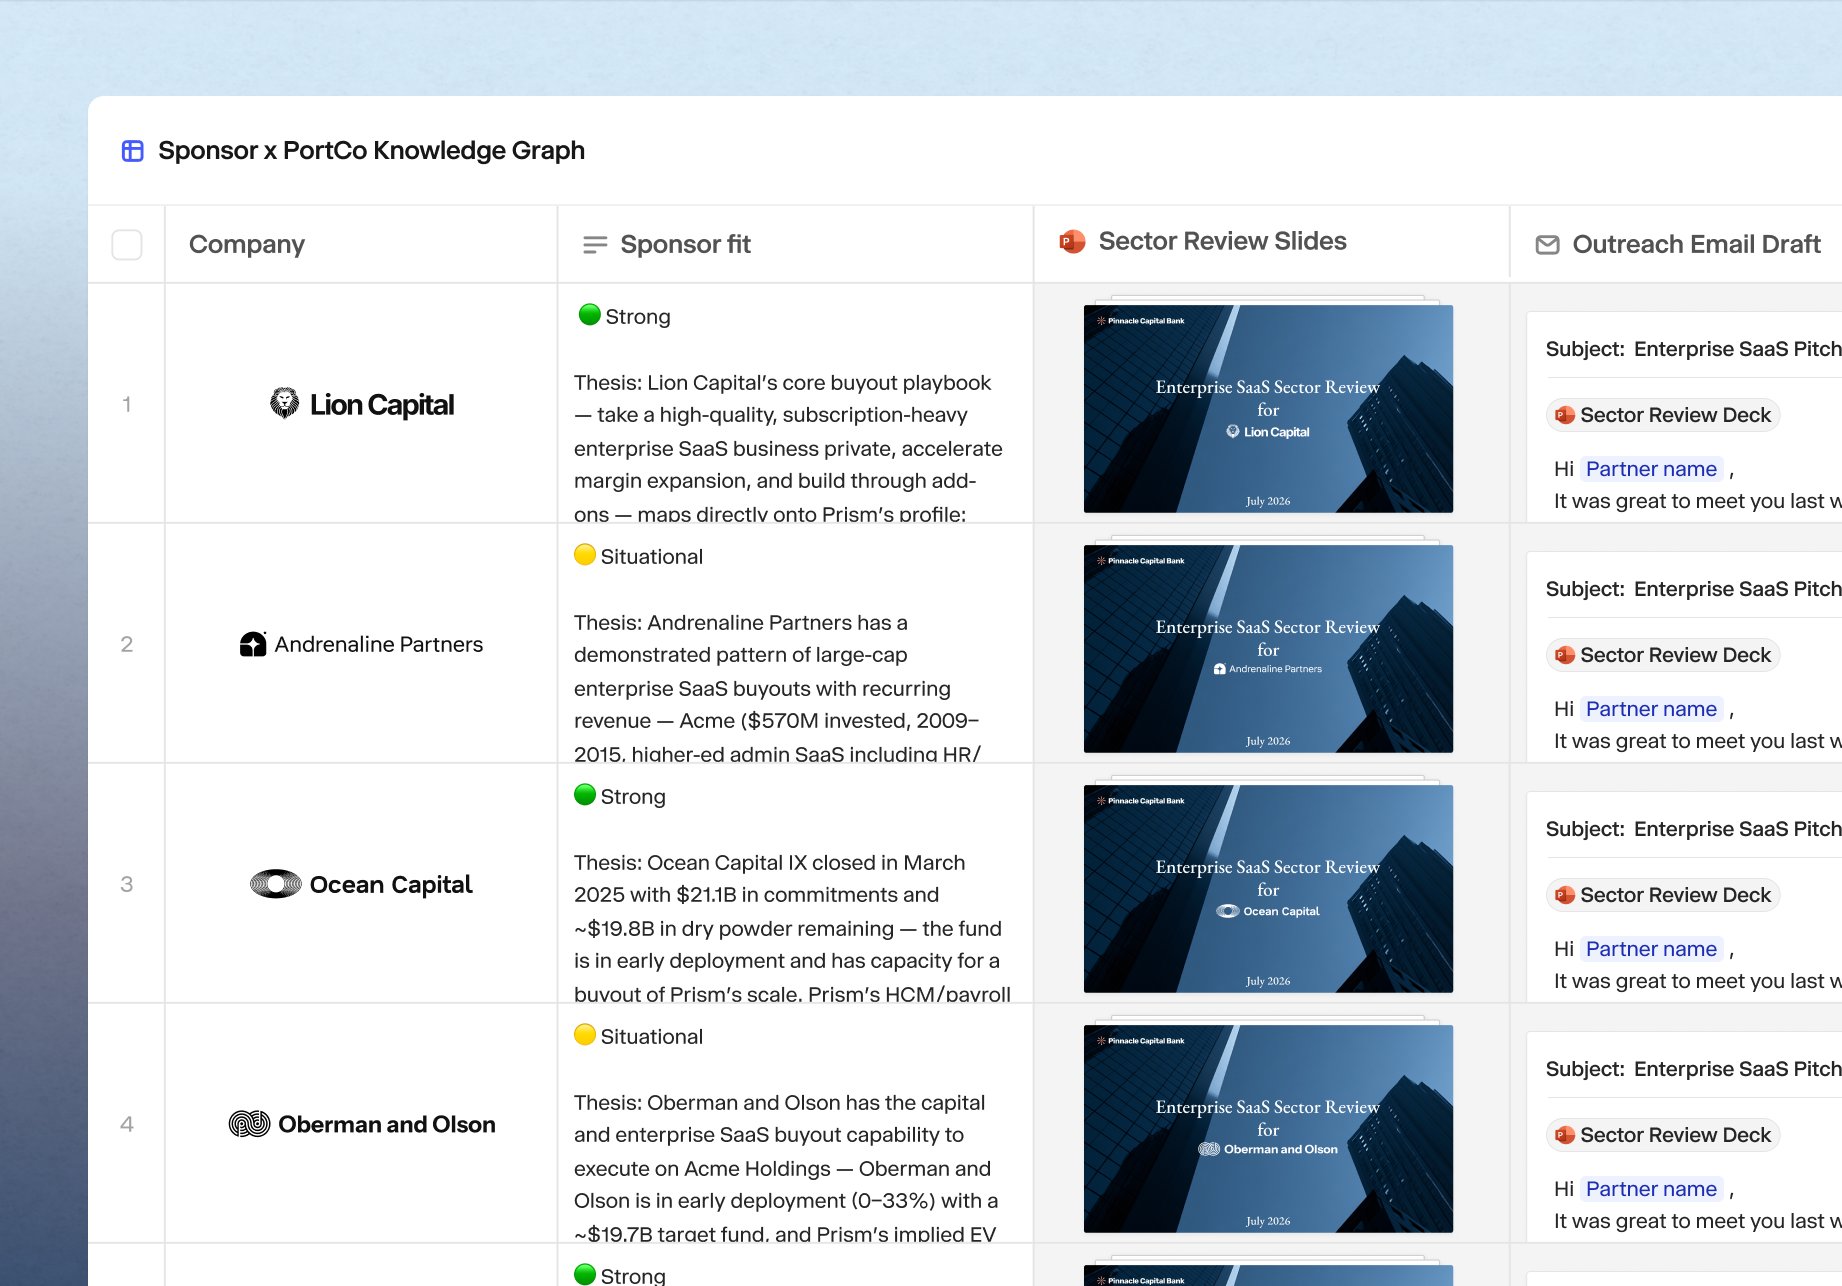
Matrix: documents are rows, questions are columns, every cell is a cited answer — "read these 500 credit agreements and extract the EBITDA definition" as one operation. Plus Draft (branded memos/decks) and reusable no-code agents. Customers: KKR, BlackRock, Carlyle, Centerview, MetLife — and in credit, Oak Hill Advisors ($108B): 6x ROI claim, credit-agreement agents deployed firm-wide.
Who uses it daily & what they do
- Bulk credit-agreement review: EBITDA definitions, add-back caps, Serta/J.Crew-risk flags across hundreds of agreements
- IC memo archive as a precedent library ("pricing on deals >$50M EBITDA and >6x leverage")
- Data-room first pass: index VDR, pull contract terms, consolidate financials, flag risks
- Origination screening: filings/transcripts for 2026 maturities, covenant-relief talk
Demos (best public demo footage on this list)
Matrix launch film (Mar 2024) — the grid UI.
Matrix demo from Series B coverage — rows/columns/citations, agent step decomposition.
Independent tutorial walkthrough (Jun 2025).
2026 finance use-cases overview.
What users say (real reviews — the only company with them)
Bottom line
The reference for extraction UX (grid + citations) — and the cautionary tale: even the category leader isn't trusted without manual verification, and users won't let it near the model. Extraction ≠ decisioning. Per-seat pricing fences it out of the lower-mid-market.
Rogo Sell-side AI analyst
Sell-side; trust gap visiblerogo.ai · NYC + London
What it actually is
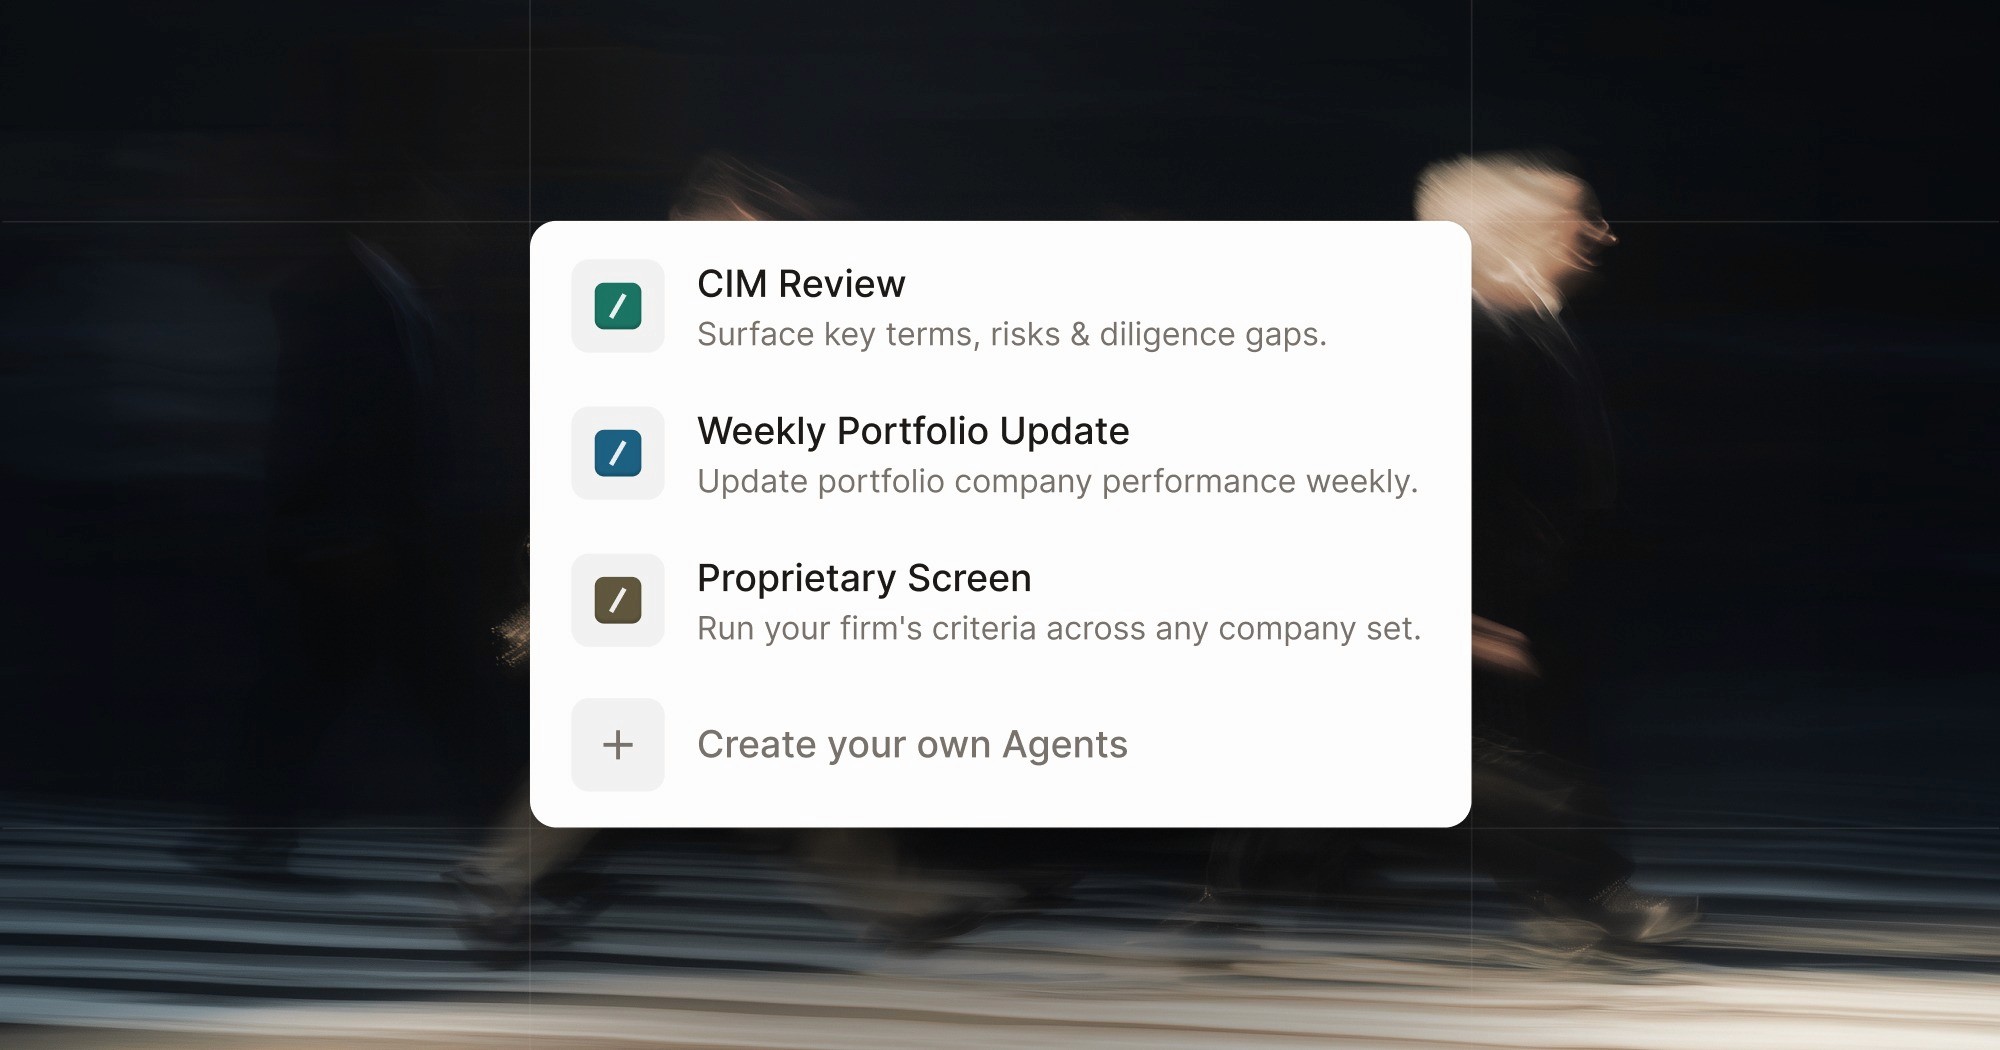
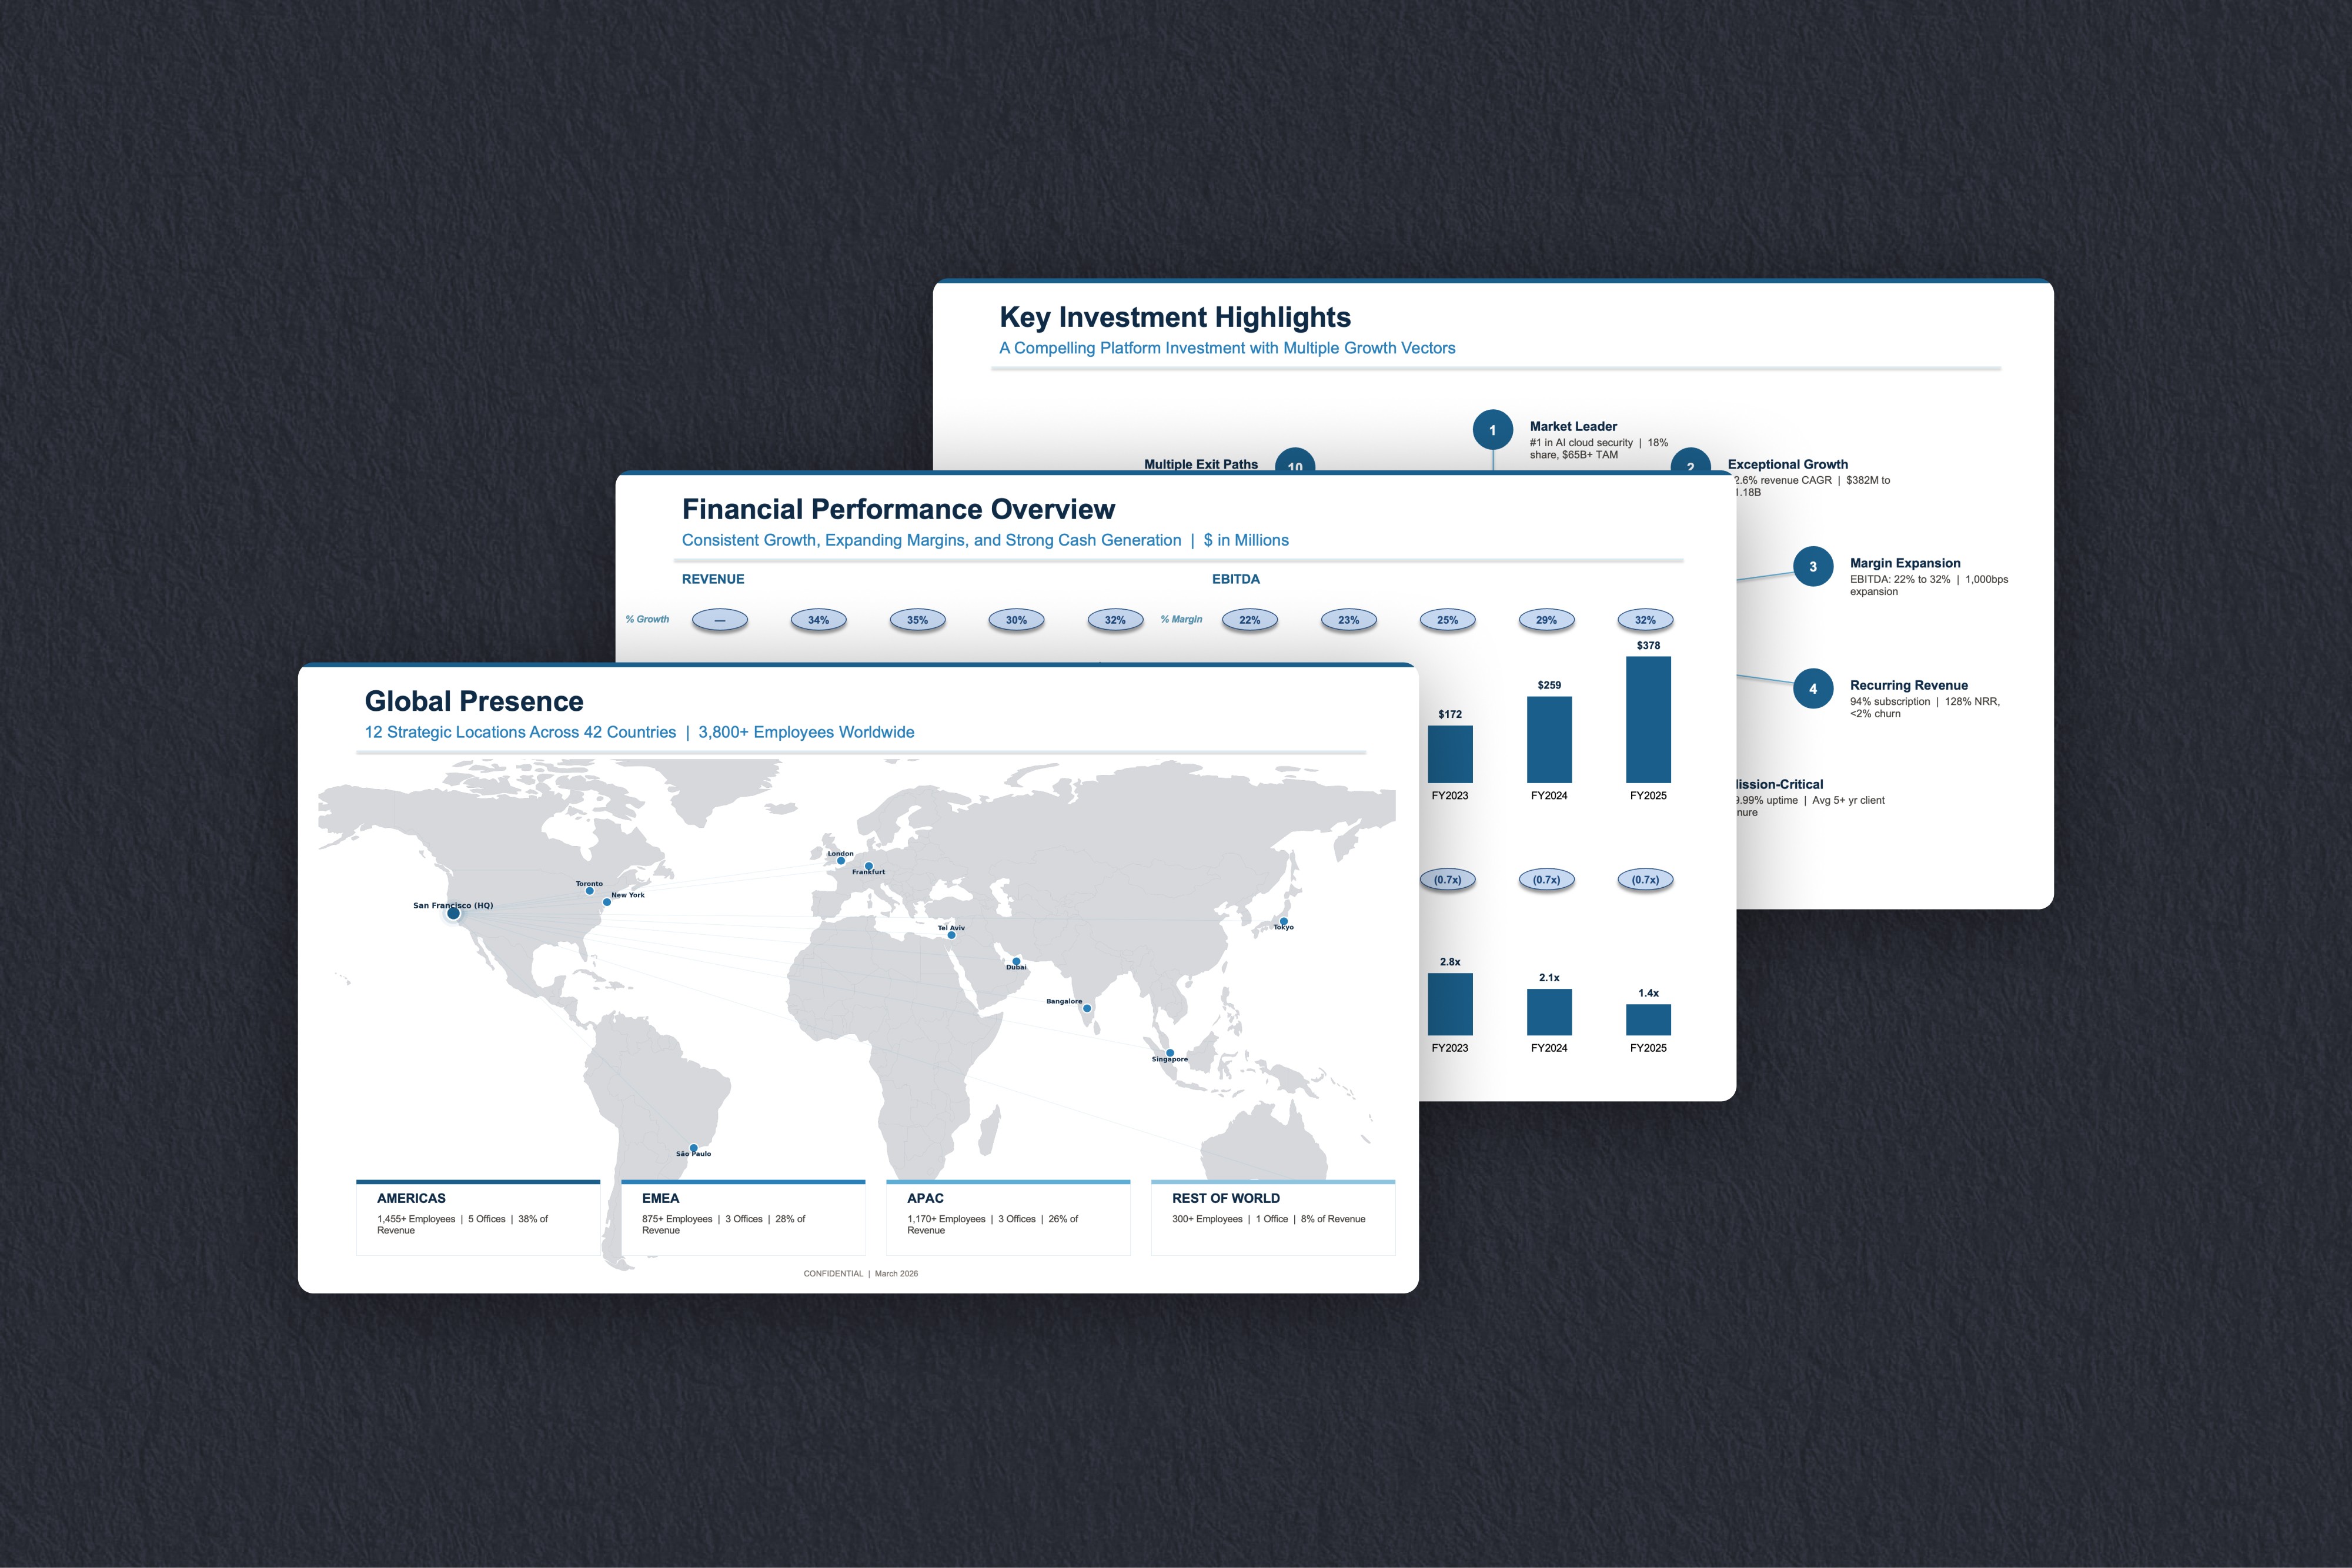
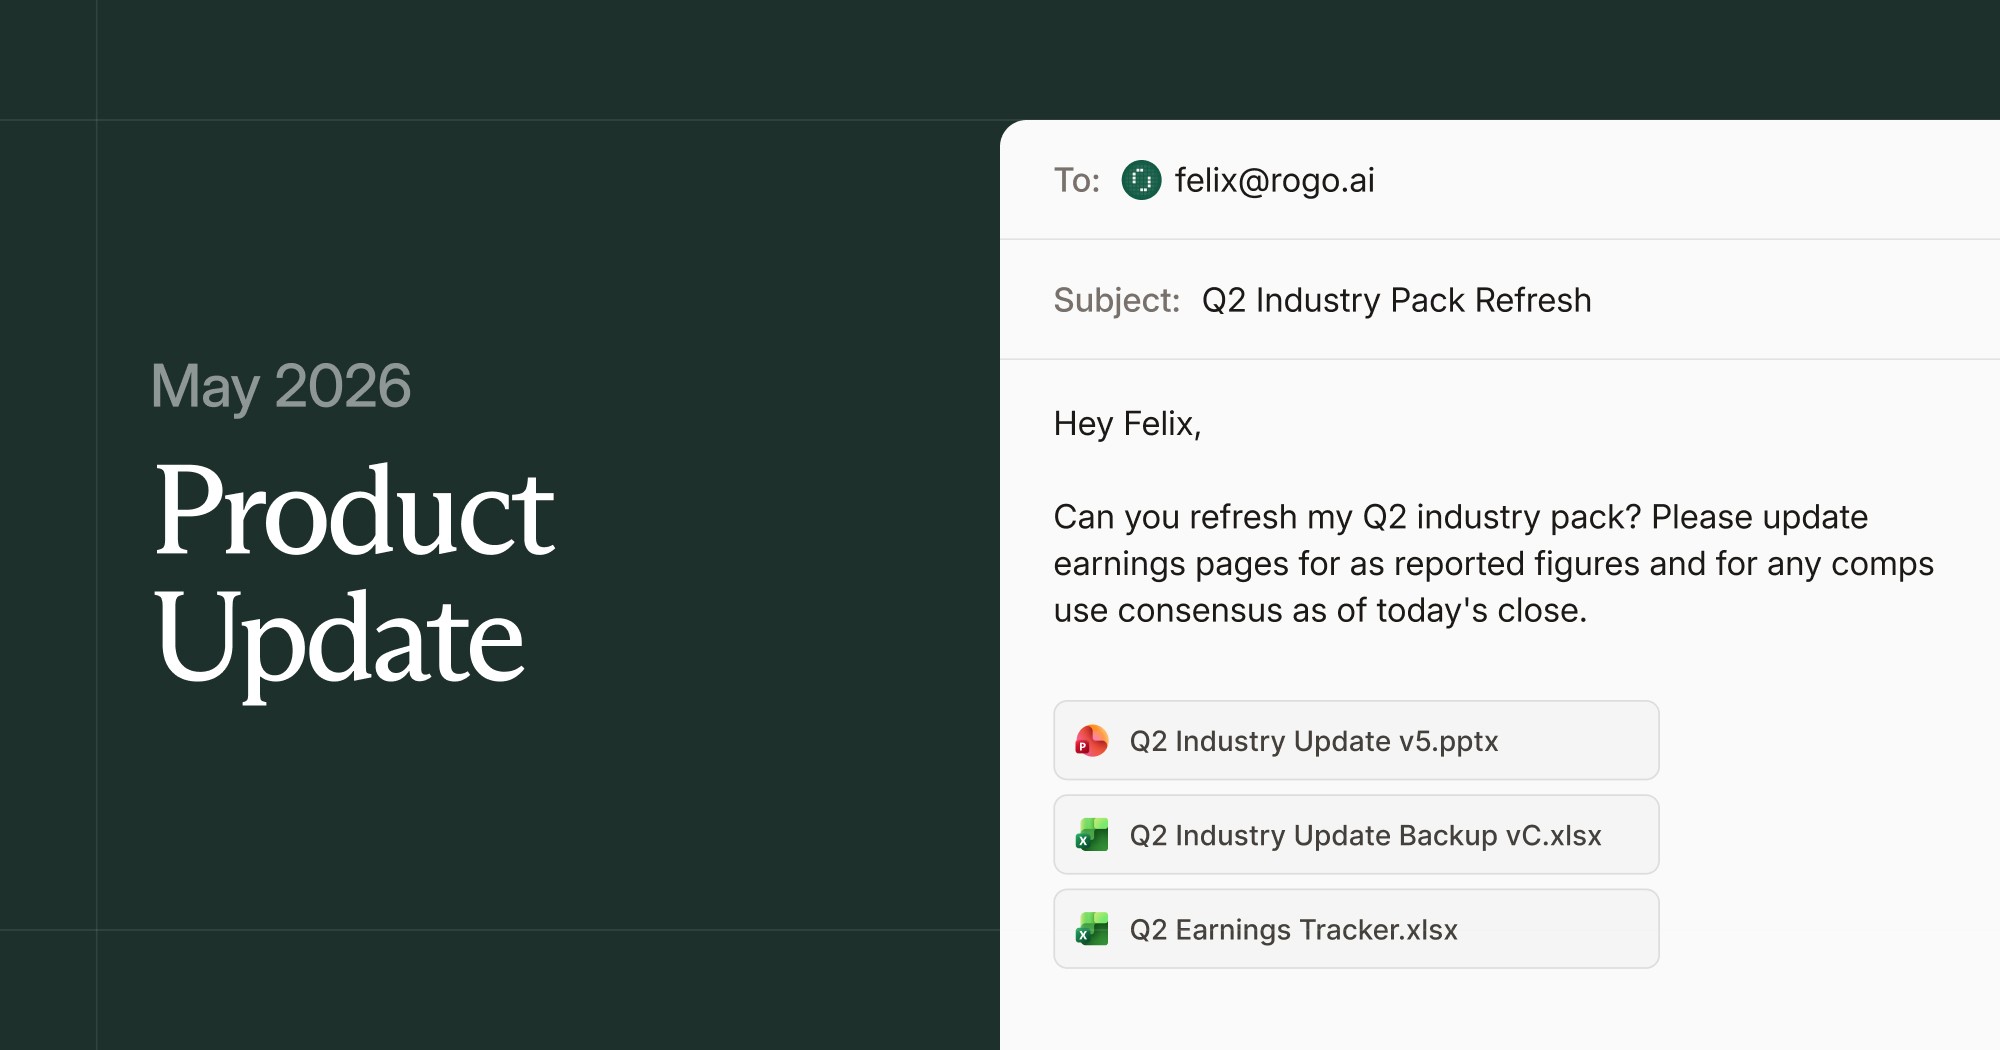
Chat research workspace + "Felix" email agent returning finished decks/models/memos in house templates. Customers are banks first — Rothschild, Jefferies, Lazard, Moelis, Baird (600 IBD users, ~10K workflows/week) — buy-side second (Tiger Global, GTCR). Data spine: LSEG, FactSet, CapIQ, PitchBook, Moody's (~65M documents). No named private credit customers; no monitoring or LP-reporting surface.
Demos
Independent hands-on attempt at the product (ScrollTalk, Oct 2024).
CEO Gabe Stengel walks through automated benchmarking/earnings/pitch workflows (Lightspeed's Generative Now).
What users say (Wall Street Oasis — analysts at banks that deployed it)
Bottom line
The market's loudest, best-funded horizontal "AI analyst" still fails the trust test with its own users ("have to check anything"). That trust gap — decision-grade, source-linked, deterministic output — is the open problem in this whole category.
All claims sourced from company sites, press, funding announcements, G2/Trustpilot/Wall Street Oasis, and public interviews as of 4 July 2026. Videos stream from YouTube/Loom.